For Americans planning retirement, Social Security terminology can be difficult to navigate. Terms such as “early eligibility age,” “full retirement age” and “delayed retirement credits” describe different points in the claiming process, but they do not always make the financial consequences immediately clear.
That is the issue behind the Claiming Age Clarity Act. The legislation focuses on how the Social Security Administration describes the ages at which people can begin receiving retirement benefits.
The important point for retirees is that the legislation does not simply raise or lower the ages at which Social Security can be claimed. Instead, it would replace several familiar terms with descriptions that more directly explain the relationship between claiming age and the size of a monthly benefit.
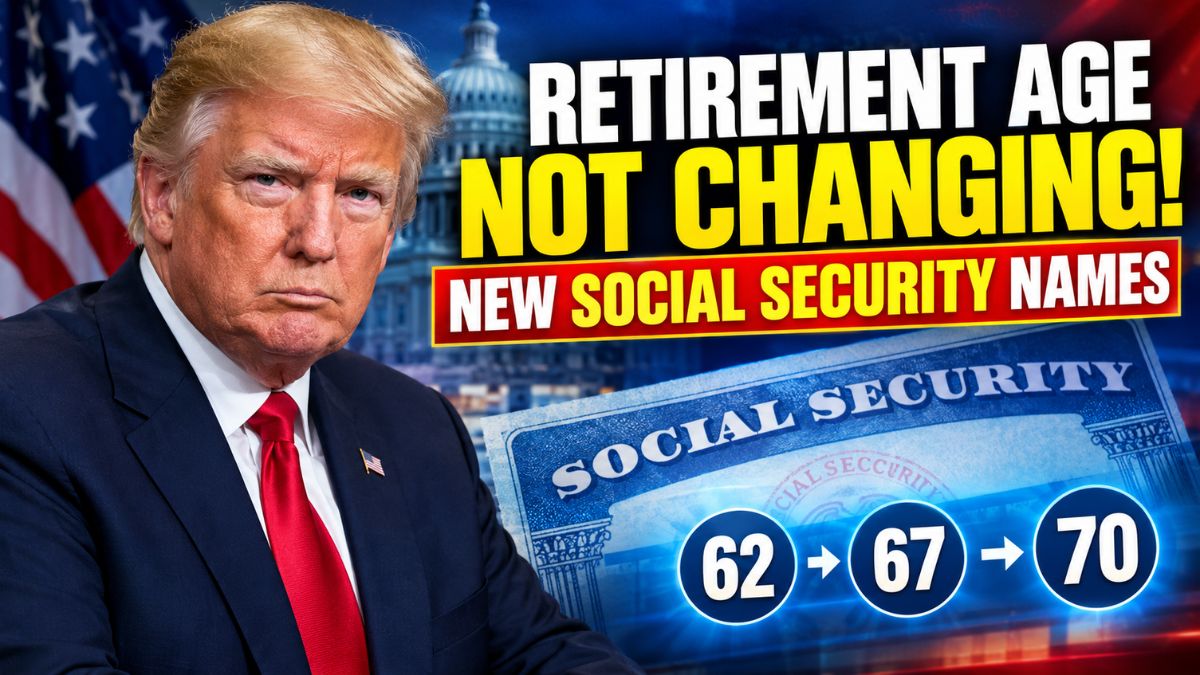
Under the proposed terminology, age 62 would become the “minimum monthly benefit age.” Full retirement age would become the “standard monthly benefit age,” while age 70 would become the “maximum monthly benefit age.”
The change may appear largely technical, but the terminology matters because the age at which someone claims Social Security can have a lasting effect on monthly income.
For official information on current Social Security retirement rules, the Social Security Administration’s retirement benefits page provides details on eligibility and claiming. The SSA also explains full retirement age based on birth year. Its retirement benefit planner provides additional information about claiming decisions.
Current
Under current Social Security rules, most people can begin receiving retirement benefits at age 62. However, claiming at that age generally results in a lower monthly benefit than waiting until full retirement age.
Full retirement age depends on a person’s year of birth. For people born in 1960 or later, the full retirement age is 67.
Workers can also choose to delay retirement benefits beyond full retirement age. For people whose full retirement age is 67, delaying benefits until age 70 can result in a higher monthly payment because of delayed retirement credits.
These three points are central to understanding the proposed terminology:
| Claiming point | Current concept | Proposed terminology |
|---|---|---|
| Age 62 | Earliest eligibility for retirement benefits | Minimum monthly benefit age |
| Full retirement age | Age for receiving the full scheduled retirement benefit | Standard monthly benefit age |
| Age 70 | Point at which delayed retirement credits stop increasing benefits | Maximum monthly benefit age |
The terminology would change the way these milestones are described, but the underlying ages would not be shifted by the legislation.
That distinction is important for anyone who has heard that Congress is “changing the retirement age.” The legislation is primarily a change in terminology and presentation rather than a new set of Social Security claiming ages.
Age 62
Age 62 would remain the earliest age at which most Americans can begin receiving Social Security retirement benefits.
The proposed name, “minimum monthly benefit age,” is intended to emphasize a financial consequence that can be easy to overlook. Starting benefits early generally means receiving a smaller monthly payment for life compared with waiting until full retirement age.
For a person whose full retirement age is 67, claiming at 62 can reduce the retirement benefit by as much as 30%.
That reduction does not mean claiming at 62 is necessarily a poor decision. Social Security decisions depend on individual circumstances. Someone may need the income because of health problems, a job loss, insufficient savings or other household expenses.
The practical issue is that taking benefits early means accepting a lower monthly amount in exchange for receiving payments sooner.
This is one reason the proposed terminology focuses on the monthly benefit rather than simply calling age 62 an eligibility milestone.
A person deciding whether to claim at 62 is not only asking, “Am I allowed to claim?” They are also asking, “How much will I receive each month if I claim now?”
Age 67
The phrase “full retirement age” is among the most familiar terms in Social Security planning. Under the proposed legislation, it would instead be called the “standard monthly benefit age.”
For people born in 1960 or later, that age remains 67.
The change in wording does not mean that everyone in the United States would have a full retirement age of 67. Social Security’s full retirement age varies by birth year, so workers should check their individual circumstances rather than assuming the same age applies to everyone.
The term “standard monthly benefit age” is designed to communicate that waiting until this milestone avoids the early claiming reduction that applies when someone starts benefits before full retirement age.
It also provides a reference point for understanding delayed retirement credits.
In other words, age 67 is not becoming a new retirement requirement. It remains a calculation point in the Social Security benefit formula for people whose full retirement age is 67.
Age 70
Age 70 represents another important point in Social Security planning.
For workers with a full retirement age of 67, delaying retirement benefits after 67 can increase the monthly benefit through delayed retirement credits. Those credits generally continue until age 70.
For someone with a full retirement age of 67, waiting until age 70 can increase the monthly retirement benefit by up to 24% compared with claiming at full retirement age.
The proposed term “maximum monthly benefit age” is intended to make this relationship easier to understand.
Once a person reaches 70, there is generally no additional increase in the retirement benefit for continuing to delay the claim.
That does not necessarily mean everyone should wait until 70. Delaying benefits means giving up several years of potential Social Security payments in exchange for a larger monthly benefit later.
The right choice can depend on health, life expectancy, financial resources, taxes, marital status and other sources of retirement income.
Terminology
Why change the terminology at all?
The legislation is based on the idea that the existing language may not clearly communicate the financial consequences of claiming at different ages.
“Early eligibility age,” for example, tells someone that they can qualify for benefits. It does not immediately tell them that claiming at that point can result in a permanently reduced monthly benefit.
Similarly, “full retirement age” can be interpreted as the age when a person should retire. That is not what the term means. A person can continue working after full retirement age, and reaching full retirement age does not require someone to stop working.
The proposed language attempts to place the monthly benefit at the center of the explanation.
The distinction matters because Social Security retirement benefits are not simply an on-or-off benefit. The timing of a claim can affect the amount a person receives each month.
Clearer terminology could therefore help workers understand the trade-off before they make a claiming decision.
Decisions
Even if the new names are adopted, Americans will still face the same basic question: When should I claim Social Security?
There is no single answer that applies to every retiree.
Claiming at 62 can provide income earlier, which may be important for someone with limited savings. However, the monthly benefit is generally lower than it would be if the person waited.
Waiting until full retirement age can provide a larger monthly payment than claiming early.
Delaying beyond full retirement age can increase the monthly benefit further, up to age 70.
This creates a trade-off between time and payment size. Taking benefits earlier means receiving more checks sooner, while delaying can mean fewer years of payments but a larger monthly amount later.
That is why the new terminology should not be interpreted as an instruction to delay benefits. It is better understood as an effort to make the financial consequences of different claiming ages more apparent.
Full
Another source of confusion is the phrase “full retirement age.”
The term does not mean that a person must retire at that age. Someone can continue working and earning income after reaching full retirement age.
It also does not mean that Social Security will replace a person’s entire previous salary.
Instead, full retirement age is a key point in the calculation of retirement benefits. Claiming before that age can result in a reduction, while delaying benefits after that age can result in delayed retirement credits until age 70.
For people born in 1960 or later, the full retirement age is 67. Other birth years have different full retirement ages.
This is why checking an individual’s Social Security record and official benefit estimate remains important when planning.
Benefits
The proposed terminology also highlights a broader issue with Social Security planning: the monthly benefit is only one part of the decision.
A retiree may need to consider Social Security alongside a 401(k), IRA, pension, investment income, employment income and personal savings.
Taxes can also affect the amount of money a household ultimately keeps.
Married couples may have additional considerations because each spouse’s claiming decision can affect the household’s overall retirement income strategy. Survivor benefits can also matter when deciding when one or both spouses should claim.
Health and expected longevity are important as well. Someone who expects to live for many decades may place greater value on a larger monthly benefit later in life. Someone facing serious health concerns may have different priorities.
The proposed names cannot resolve those questions. They can only make the basic claiming framework easier to understand.
Impact
The key question is whether changing the terminology will actually change behavior.
It could help some people, particularly those who are unfamiliar with Social Security rules. A label that explicitly refers to a “minimum monthly benefit” may make the financial consequence of claiming at 62 more apparent than the phrase “early eligibility age.”
However, terminology is only one factor in a retirement decision.
People may claim early because they need income. Others may delay because they have enough savings to wait. Some may continue working and postpone Social Security because they want to maximize their eventual monthly payment.
There is also a behavioral element. People often prefer receiving money sooner rather than later, particularly when the future is uncertain.
For that reason, it would be difficult to conclude that new terminology alone will cause a major shift in claiming patterns.
What
The Claiming Age Clarity Act is best understood as a change in how Social Security claiming ages are described.
The three central terms would become:
- Age 62: “minimum monthly benefit age”
- Full retirement age: “standard monthly benefit age”
- Age 70: “maximum monthly benefit age”
For people born in 1960 or later, the standard monthly benefit age would correspond to age 67.
The proposed names are designed to focus attention on monthly income rather than eligibility alone.
That could make Social Security information easier for workers to interpret, particularly when they are comparing the consequences of claiming at 62, waiting until full retirement age or delaying until 70.
But the legislation does not turn age 62 into a new retirement age, move age 67 to another point or create a new age 70 benefit rule.
Planning
For someone approaching retirement, the most useful response to the proposed terminology is not to change a claiming strategy immediately. Instead, it is to understand how the benefit amount changes at different ages.
A person can start by checking their estimated Social Security benefits through the Social Security Administration. Comparing estimates at different claiming ages can help show the financial difference between taking benefits early and waiting.
It is also worth considering the broader retirement picture. Social Security may be one income source among several, and the best claiming decision can depend on how those sources work together.
People should also be cautious about treating a single percentage or claiming age as a universal recommendation. A higher monthly benefit is valuable, but waiting to receive it has a cost because the person gives up benefits that could have been collected earlier.
The new terminology may eventually make that trade-off easier to communicate. But the underlying decision remains personal and financial rather than simply linguistic.
The central takeaway is straightforward. The Claiming Age Clarity Act is not, by itself, a proposal to move the Social Security retirement ages. Age 62 remains the earliest claiming point under current rules, full retirement age remains dependent on birth year and is 67 for people born in 1960 or later, and age 70 remains the point through which delayed retirement credits can increase benefits. What could change is the language Americans see when they learn about those milestones. For anyone planning retirement, the more important question remains the same: how will the age I choose affect my monthly Social Security income and my overall retirement plan?