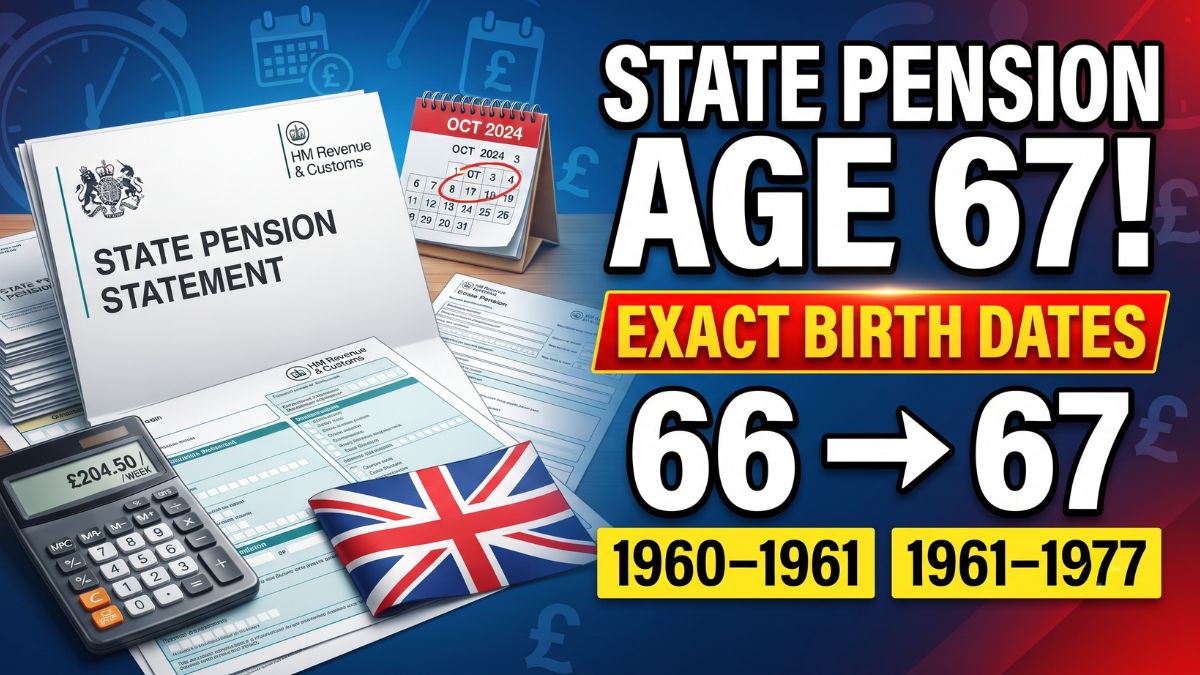
The UK State Pension age is moving from 66 to 67, and the change is being introduced gradually rather than on a single date.
The Department for Work and Pensions (DWP) has published the timetable showing when people born in particular date ranges will reach State Pension age. For some people born between April 1960 and March 1961, the increase is phased month by month. For those born from March 6, 1961, through April 5, 1977, the State Pension age is 67.
The change is not new legislation announced unexpectedly. The increase from 66 to 67 was established through the Pensions Act 2014, which brought forward the timetable for the increase. The government says the change will be completed by 2028.
For anyone approaching retirement, the key issue is therefore not simply whether the State Pension age is 67. It is determining the exact age that applies based on your date of birth.
The official GOV.UK State Pension age page provides the current rules and a calculator for checking an individual’s State Pension age. The State Pension forecast service can also help people review their expected entitlement. Further information on the legislation and timetable is available through the Pensions Act 2014.
Increase
The State Pension age is currently 66 for men and women.
It is now increasing to 67 between 2026 and 2028.
The increase does not mean everyone reaches State Pension age on the same day. Instead, the government created a phased timetable for people born between April 6, 1960, and March 5, 1961.
During that period, the State Pension age rises by one month for each successive birth-date group.
After that transitional period, people born from March 6, 1961, to April 5, 1977, will reach State Pension age at 67.
This approach means two people born only a few weeks apart could have different State Pension ages.
That is why checking the exact date of birth is important when planning retirement.
Timetable
The DWP timetable for the increase from 66 to 67 is as follows:
| Date of birth | State Pension age |
|---|---|
| April 6, 1960 – May 5, 1960 | 66 years, 1 month |
| May 6, 1960 – June 5, 1960 | 66 years, 2 months |
| June 6, 1960 – July 5, 1960 | 66 years, 3 months |
| July 6, 1960 – August 5, 1960 | 66 years, 4 months |
| August 6, 1960 – September 5, 1960 | 66 years, 5 months |
| September 6, 1960 – October 5, 1960 | 66 years, 6 months |
| October 6, 1960 – November 5, 1960 | 66 years, 7 months |
| November 6, 1960 – December 5, 1960 | 66 years, 8 months |
| December 6, 1960 – January 5, 1961 | 66 years, 9 months |
| January 6, 1961 – February 5, 1961 | 66 years, 10 months |
| February 6, 1961 – March 5, 1961 | 66 years, 11 months |
| March 6, 1961 – April 5, 1977 | 67 years |
The timetable shows why simply saying “the State Pension age is rising to 67” does not provide the complete picture.
For someone born in the first part of the transition period, State Pension age can be somewhere between 66 years and one month and 66 years and 11 months.
For later birth dates within the specified period, it reaches 67.
Dates
People born between April 6, 1960, and March 5, 1961, are the main group affected by the monthly phase-in.
For example, someone born between April 6 and May 5, 1960, reaches State Pension age at 66 years and one month.
Someone born between February 6 and March 5, 1961, reaches State Pension age at 66 years and 11 months.
The following group, born from March 6, 1961, onward through April 5, 1977, has a State Pension age of 67 under the timetable.
This gradual approach was introduced so that the increase did not take place abruptly for everyone.
The DWP has said people affected by changes to their State Pension age will receive correspondence. Nevertheless, individuals approaching retirement may want to check their own State Pension age rather than relying solely on general dates reported in news coverage.
Legislation
The increase is rooted in legislation rather than being a recent administrative decision.
The Pensions Act 2014 brought forward the increase in State Pension age from 66 to 67 by eight years.
The legislation also changed how the increase would be phased.
Previously, a person could be given a particular date for reaching State Pension age. Under the revised arrangements, the transitional group reaches State Pension age at a specified age measured in years and months.
The change was designed to spread the increase across the affected birth dates.
The government has also legislated for a later increase in State Pension age from 67 to 68, although the timetable for that future change is subject to review.
Age
The State Pension age should not be confused with the age at which a person has to stop working.
There is no general requirement for someone to retire simply because they reach State Pension age.
A person can continue working beyond State Pension age if they choose and if their employment circumstances allow it.
Likewise, reaching State Pension age does not mean that someone has to claim their State Pension immediately in every circumstance. People can choose to defer their State Pension, although the financial consequences of deferring should be considered carefully.
This distinction matters because “State Pension age” describes when a person becomes eligible to receive the State Pension under the relevant rules. It is not a mandatory retirement age.
Pension
The amount a person receives from the State Pension is also separate from the question of when they reach State Pension age.
Eligibility and the amount payable depend on an individual’s National Insurance record and other relevant circumstances.
Under the new State Pension system, a person generally needs at least 10 qualifying years on their National Insurance record to receive any new State Pension, while 35 qualifying years is the figure generally associated with receiving the full new State Pension for someone with a straightforward National Insurance record.
However, individual records can be more complicated. Contracting out and other factors can affect the calculation.
For that reason, reaching State Pension age does not automatically mean everyone receives the same amount.
People approaching retirement should check their State Pension forecast to understand what they are currently expected to receive.
Planning
The increase to 67 makes retirement planning particularly important for people in the affected birth-date groups.
Someone who had expected to receive the State Pension at 66 may now need to plan for an additional period before State Pension income begins.
That could mean continuing to work, using personal savings, drawing from a workplace pension or considering other sources of retirement income.
The financial effect will vary from household to household.
For someone with substantial private pension savings, an additional year before State Pension age may be manageable. For someone relying heavily on the State Pension, the change could require more careful budgeting.
It is therefore useful to identify the exact State Pension age early rather than waiting until retirement is close.
Review
The government is legally required to review the State Pension age periodically.
The purpose of these reviews is to consider factors such as changes in life expectancy and the sustainability of the State Pension system.
The government has previously set out plans for a future increase from 67 to 68, with the increase currently scheduled for 2044 to 2046 under existing legislation.
However, the timing of future State Pension age changes can be reviewed and potentially altered.
This means people born after the current transition period should check the latest government guidance when making long-term retirement plans.
A State Pension age shown in a long-range projection should not necessarily be treated as permanently fixed decades in advance.
Messages
The DWP has said that people affected by the changes will receive correspondence about their State Pension age.
The department has also directed people to the government’s State Pension calculator, which can provide an individual answer based on date of birth.
Checking directly with the government is particularly useful because general articles can simplify a timetable that actually contains several different birth-date groups.
For people born around the transition dates, a difference of only a few weeks can affect the applicable State Pension age.
It is also worth checking the State Pension forecast separately, because knowing when you can claim is different from knowing how much you may receive.
Future
The current increase from 66 to 67 is scheduled to be completed by 2028.
The transitional timetable means the change is already being introduced for people in the relevant birth-date groups.
For those born from March 6, 1961, through April 5, 1977, the State Pension age is 67 under the current timetable. People born after that period may have a different State Pension age depending on future legislation and reviews.
The planned later increase to 68 is another reason for people to check the latest government information rather than assuming today’s rules will remain unchanged throughout their working lives.
For now, the immediate issue is clear: the UK State Pension age is rising from 66 to 67, with the change being phased between 2026 and 2028. People born between April 6, 1960, and March 5, 1961, move through the transition in monthly stages, while those born from March 6, 1961, to April 5, 1977, have a State Pension age of 67 under the current timetable. The change does not require people to stop working at 67, and it does not by itself determine the amount of State Pension they will receive. Anyone affected should check their exact State Pension age and forecast through GOV.UK and factor the result into their wider retirement plans.