Social Security recipients are watching the 2027 Cost-of-Living Adjustment (COLA) closely as inflation continues to shape household budgets. The annual adjustment is intended to help retirement, disability, and survivor benefits keep pace with changes in consumer prices. However, the headline increase is only one part of the picture for retirees.
The 2027 COLA is scheduled to be announced on October 14, 2026. The adjustment will apply to Social Security benefits beginning in December 2026 for some recipients, with the broader January 2027 payment schedule reflecting the new benefit amounts. The Social Security Administration’s official COLA information explains how the annual adjustment is determined.
Forecast
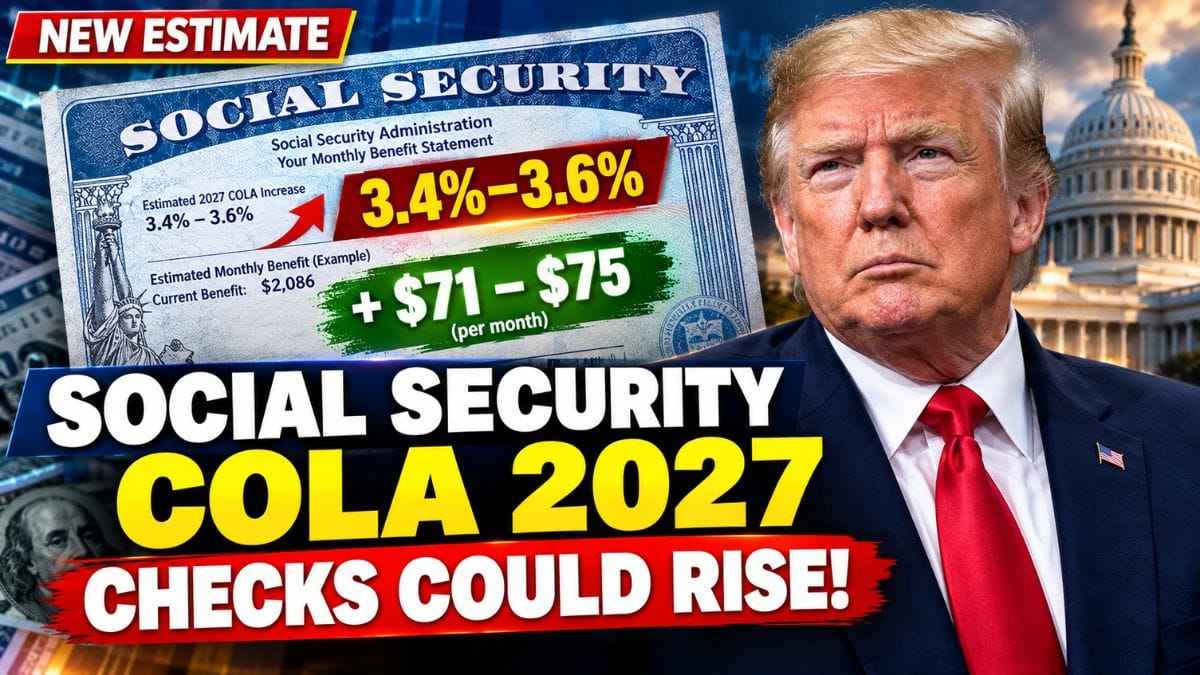
Current forecasts from the Senior Citizens League and AARP point to a 2027 Social Security COLA of roughly 3.5% to 3.6%. These figures are estimates, not the final adjustment. The official COLA will be determined using the government’s inflation calculation.
For retirees, the difference between the two estimates may appear small. However, even a fraction of a percentage point can translate into several dollars per month depending on the size of an individual’s benefit.
A 3.6% adjustment, based on the average Social Security check cited in current estimates, could add around $75 per month. A 3.5% increase could add approximately $68.
| Estimated COLA | Approx. Monthly Increase |
|---|---|
| 3.5% | $68 |
| 3.6% | $75 |
The actual dollar increase will vary from one beneficiary to another. Someone receiving more than the average benefit could see a larger dollar increase, while a person receiving less could receive a smaller increase.
The SSA’s COLA page provides the official adjustment once it is announced and explains the historical annual changes.
Medicare
One reason retirees should look beyond the headline COLA percentage is Medicare. Changes in Medicare premiums can affect how much of a Social Security increase remains available for other household expenses.
For example, in 2026, Social Security benefits received a 2.8% COLA. The standard Medicare Part B premium was also set at $202.90 per month, with a $283 annual deductible.
Medicare premiums are separate from the Social Security COLA calculation. As a result, retirees need to consider both when estimating their actual change in monthly cash flow.
The relationship is fairly straightforward: if Social Security income rises while healthcare expenses also increase, the net improvement in a household budget may be smaller than the COLA percentage suggests.
Retirees can review current Medicare premium information through the official Medicare website, which provides details about Part B, Part D and other Medicare costs.
IRMAA
Another consideration is the income-related monthly adjustment amount, commonly known as IRMAA. This surcharge can increase Medicare Part B and Part D premiums for beneficiaries with higher incomes.
Medicare generally uses modified adjusted gross income from two years earlier when determining IRMAA. Consequently, income received in one year can affect Medicare premiums in a later year.
A higher Social Security benefit does not automatically mean that someone will face an IRMAA surcharge. However, retirees who are already close to an applicable income threshold should consider their total income rather than looking at the COLA in isolation.
For example, a household near an IRMAA threshold could experience a change in Medicare premiums if its income moves into another bracket. The effect can be considerably larger than the additional Social Security payment itself.
This is why the timing of income also matters in retirement planning. A beneficiary may see a higher Social Security check while simultaneously facing changes in Medicare costs based on income from an earlier tax year.
Taxes
Federal taxes are another factor that can affect the value of a Social Security increase.
Social Security benefits can be taxable depending on a person’s overall income and filing status. A COLA raises the amount of Social Security received during the year, which can affect a household’s overall income calculation.
That does not mean every retiree will owe more tax after a COLA increase. The outcome depends on factors such as filing status, other sources of income and the amount of Social Security benefits received.
For retirees, the broader issue is that the amount shown on a Social Security statement is not necessarily the same as the amount ultimately available for spending.
Impact
The financial effect of the 2027 COLA will differ significantly between households.
Someone who relies primarily on Social Security and has relatively limited Medicare and tax exposure may retain most of the additional benefit. Another retiree with substantial retirement income could have a different result if Medicare premiums, IRMAA or taxes increase.
This makes the percentage itself an incomplete measure of the adjustment’s financial impact.
For example, a 3.5% increase and a 3.6% increase may produce only a modest difference in a monthly check. But if a household’s healthcare expenses rise at the same time, the additional Social Security income may have less effect on its overall budget.
The same principle applies to everyday expenses. Housing, food, utilities, insurance and healthcare do not necessarily rise at the same rate as the inflation measure used to calculate the Social Security COLA.
Payments
The timing of Social Security payments can also cause confusion around the 2027 COLA.
The higher benefit amounts are associated with the January 2027 payment cycle. However, Social Security payments are generally made according to a schedule based on a beneficiary’s birth date, and some payments can arrive in the previous month when a scheduled payment date falls on a weekend or federal holiday.
For 2027, January 1 is a federal holiday, so the payment scheduled for that date is moved to the preceding business day. Beneficiaries should therefore distinguish between the month a payment is associated with and the calendar date when the money actually reaches their account.
The Social Security Administration’s payment schedule provides the official dates beneficiaries can use to check when payments are scheduled.
Planning
Until the official 2027 COLA is released, retirees should treat the 3.5% to 3.6% figures as forecasts rather than guaranteed numbers.
One useful approach is to prepare a few household-budget scenarios. A retiree could calculate expected Social Security income using both estimates, then compare those amounts with expected Medicare premiums, taxes and other recurring expenses.
It may also be useful to review total income when considering potential IRMAA exposure. The relevant Medicare calculation is based on prior-year tax information, so decisions made today can have effects on future Medicare costs.
Ultimately, the 2027 COLA will provide an inflation adjustment, but its effect on household finances will depend on more than the percentage announced by the Social Security Administration. Medicare costs, IRMAA rules, taxes and personal spending patterns will all help determine how much of the increase remains available to retirees.