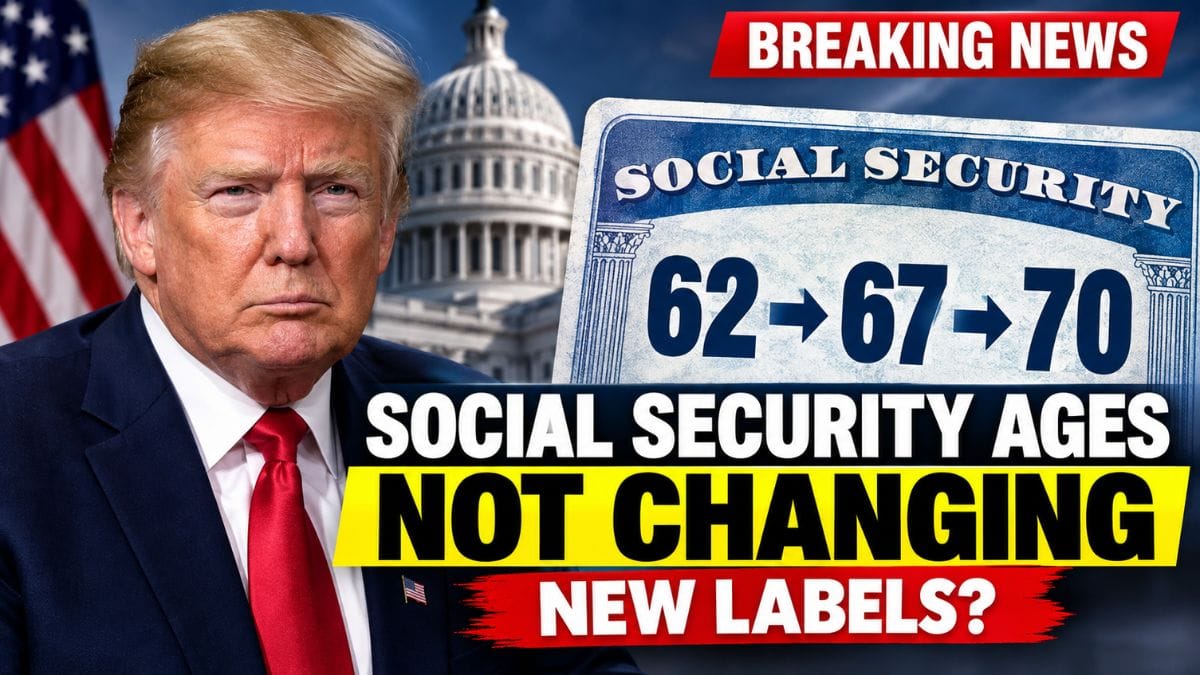
The numbers Americans use to claim Social Security retirement benefits are not being changed by the Claiming Age Clarity Act. What could change is the terminology used by the Social Security Administration (SSA) to describe those ages.
The Senate passed the Claiming Age Clarity Act on Sept. 29 by unanimous consent, sending the legislation to President Donald Trump for consideration. If it becomes law, the SSA would have to replace several terms currently used in its retirement benefit materials.
For people planning when to claim Social Security, the distinction is important. A new label does not by itself mean a new benefit formula or a different claiming age. The proposed changes are primarily about how the existing rules are explained.
Labels
The phrase “full retirement age” has been used for years to describe the age at which a person becomes eligible for 100% of their calculated retirement benefit.
The term can be confusing because it does not mean the earliest age to receive Social Security retirement benefits. Most workers can generally begin claiming at age 62. It also does not mean a person must stop working.
For people born in 1960 or later, the current full retirement age is 67.
Under the legislation, “full retirement age” and “normal retirement age” would be replaced with “standard monthly benefit age.”
The bill would also replace “early eligibility age” with “minimum monthly benefit age.” Age 70 would be described as the “maximum monthly benefit age.”
The proposed terminology is intended to put more emphasis on how the timing of a claim affects the size of the monthly payment.
Age 62
Age 62 would remain the earliest age at which most people can begin receiving Social Security retirement benefits.
Claiming at 62 allows a worker to start receiving monthly payments earlier, but the trade-off is a permanently smaller benefit compared with waiting until full retirement age.
For people born in 1960 or later, claiming at 62 can result in a retirement benefit equal to 70% of the amount payable at age 67 under the standard Social Security rules.
That reduction is not simply a temporary adjustment. The lower monthly amount generally continues after the person reaches full retirement age.
The SSA explains the effect of claiming at different ages in its official Retirement Benefits publication.
Age 67
For workers born in 1960 or later, age 67 is the current full retirement age. If the legislation becomes law, that age would instead be referred to as the standard monthly benefit age.
At 67, a worker who claims retirement benefits receives 100% of the benefit calculated under the applicable Social Security formula.
The phrase “standard monthly benefit age” is designed to describe the benefit more directly. It does not mean that workers have to retire at 67.
A person can continue working after reaching that age and can also delay claiming retirement benefits. Social Security retirement benefits and the decision to leave the workforce are separate matters.
The SSA provides an official Retirement Age Calculator that shows how full retirement age varies by birth year.
Age 70
Waiting beyond full retirement age can increase a worker’s monthly Social Security retirement benefit through delayed retirement credits.
For people born in 1943 or later, the increase is generally 8% for each full year of delay after full retirement age, up to age 70. For someone born in 1960 or later, that can produce a benefit equal to 124% of the amount payable at age 67.
The proposed legislation would call age 70 the maximum monthly benefit age.
The name reflects an important limit in the current rules. Delaying retirement benefits beyond age 70 does not produce additional delayed retirement credits.
The SSA’s official Delayed Retirement Credits information explains how those increases work.
Payments
The proposed terminology does not, by itself, change the underlying percentages associated with claiming at different ages.
For people born in 1960 or later, the current rules can be summarized as follows:
| Claiming age | Proposed label | Benefit compared with age 67 |
|---|---|---|
| 62 | Minimum monthly benefit age | 70% |
| 67 | Standard monthly benefit age | 100% |
| 70 | Maximum monthly benefit age | 124% |
These figures illustrate why claiming age matters. Starting earlier means receiving payments sooner, while waiting can result in a larger monthly payment.
The choice is not simply about finding a particular age that works for everyone. A person who claims at 62 receives several additional years of payments compared with someone who waits until 70. The person who waits, meanwhile, receives a larger monthly amount once benefits begin.
That makes the decision a question of timing as well as monthly benefit size.
Changes
If the Claiming Age Clarity Act becomes law, the SSA would need to update its terminology in rules, regulations, guidance and other materials.
The changes would apply to both online and printed information. The legislation provides a deadline based on the later of 12 months after enactment or Jan. 1, 2027.
For future retirees, this could mean seeing different terminology when reading Social Security statements, educational materials, online resources and other agency information.
The important point is that changing the words does not automatically change the underlying Social Security benefit rules.
The Senate’s official legislation page provides the congressional record for the Claiming Age Clarity Act, while the SSA remains the primary federal source for current retirement benefit rules and claiming information.
Decisions
The new terminology may make the relationship between claiming age and monthly benefits easier to describe, but it does not determine when an individual should claim.
A person’s circumstances can include employment income, household finances, taxes, health and longevity considerations, and potential benefits for a spouse or other family members.
Someone who claims at 62 generally receives a smaller monthly benefit but starts receiving payments earlier. Someone who delays can receive a larger monthly benefit, but gives up payments during the years before claiming.
The legislation itself does not resolve that trade-off. Its focus is the terminology used to explain Social Security retirement benefits.
For now, the key numbers remain familiar. Age 62 is generally the earliest claiming age, age 67 is the full retirement age for people born in 1960 or later, and age 70 is the point at which delayed retirement credits stop increasing the monthly retirement benefit.
If the bill becomes law, the main change initially may be what retirees see in Social Security materials rather than what they receive in their monthly checks. The labels would change, but the underlying claiming ages and benefit concepts described above would remain the central framework.