Social Security’s October update is approaching, and the annual announcement will include more than the cost-of-living adjustment (COLA). Several important figures used to determine Social Security taxes, benefit eligibility and the treatment of earnings for working beneficiaries are also updated each year.
The Social Security Administration (SSA) is expected to announce the 2027 figures on October 14, 2026. For retirees, workers and people already receiving benefits, the announcement will provide a clearer picture of how several parts of the program are scheduled to change next year.
Here are four numbers worth watching when the 2027 Social Security update is released.
COLA
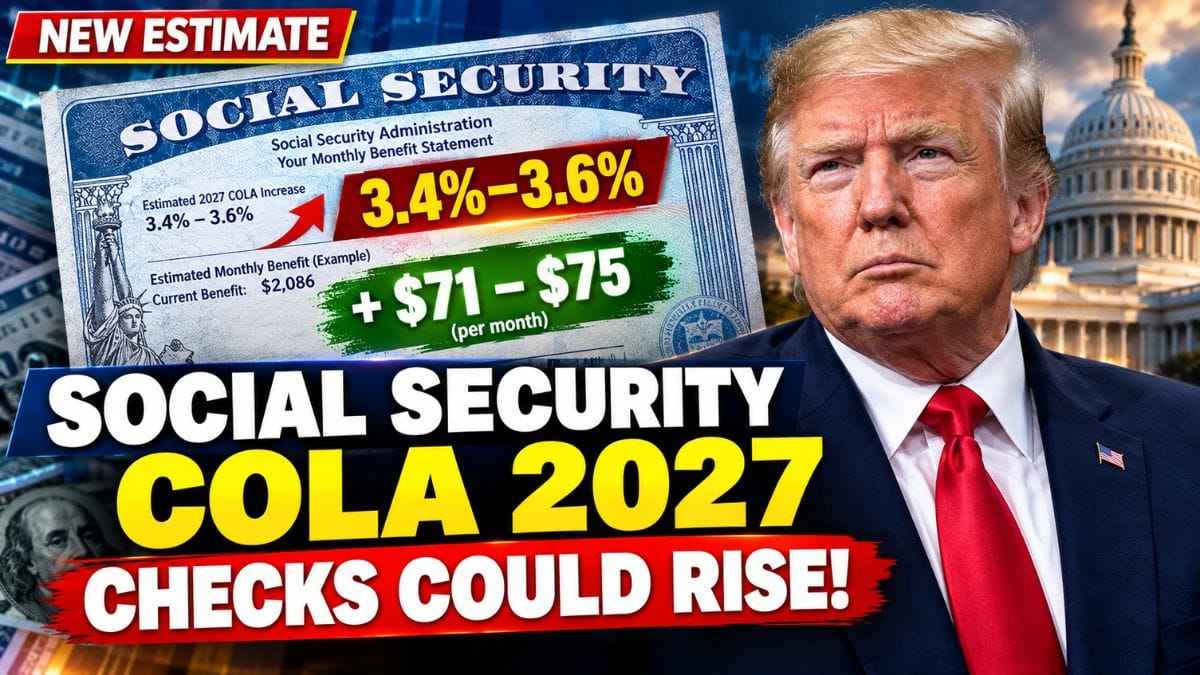
The 2027 Social Security COLA will likely receive the most attention because it determines how much monthly benefits will increase.
The Senior Citizens League has estimated that the 2027 COLA could be around 3.5%. However, that remains a forecast rather than an official figure. The final adjustment is calculated using the inflation measure specified under Social Security law and will be announced by the SSA.
The COLA applies to Social Security retirement, disability and survivor benefits. The new amount will affect payments associated with the 2027 benefit year.
For someone receiving a monthly Social Security benefit, even a relatively small percentage change can translate into a noticeable annual difference. However, the actual dollar increase depends on the person’s current benefit amount.
The official Social Security COLA information will provide the final figure once it is announced.
Taxable
The maximum amount of earnings subject to Social Security payroll taxes is another figure expected to change in 2027.
In 2026, the Social Security taxable maximum is $184,500. Earnings above that amount are not subject to the Social Security portion of payroll taxes, although other taxes may still apply.
The change primarily matters to higher earners. Most employees earn below the taxable maximum and therefore pay Social Security taxes on all of their covered wages.
Employees generally contribute 6.2% of covered wages to Social Security, while employers contribute an additional 6.2%. Self-employed workers generally pay the combined 12.4% Social Security tax rate, subject to the applicable taxable maximum.
The annual adjustment reflects changes in the national average wage index. The SSA’s contribution and benefit base information provides the official historical figures and the applicable taxable maximum.
For higher-income workers, the 2027 number will determine how much of their earnings remains subject to Social Security payroll taxes.
Credits
The amount workers must earn to receive a Social Security credit is also adjusted periodically.
Workers generally need 40 credits to qualify for Social Security retirement benefits. The number of credits a person needs does not increase from year to year, but the earnings required to earn each credit can change.
In 2026, workers receive one credit for each $1,890 in covered earnings, up to a maximum of four credits during the year. The amount required for a credit is expected to increase in 2027.
This distinction is important. A worker does not need to earn a separate amount for every credit in a single period. Instead, earnings during the year determine how many credits can be earned, subject to the annual maximum of four.
For younger workers, the change may have little practical effect because they have many years to accumulate credits. For someone closer to retirement who is trying to reach the 40-credit requirement, however, the annual earnings threshold can be more relevant.
The SSA’s Social Security credits information explains how credits are earned and how they affect eligibility.
Earnings
The fourth major change concerns Social Security’s retirement earnings test.
The earnings test can affect beneficiaries who claim Social Security before reaching full retirement age while continuing to work. The rules depend on whether the beneficiary remains below full retirement age for the entire year or reaches full retirement age during the year.
In 2026, beneficiaries who remain below full retirement age throughout the year can lose $1 in benefits for every $2 earned above $24,480.
For someone reaching full retirement age in 2026, a different limit applies. The beneficiary can earn up to $65,160 before the earnings test applies, with $1 in benefits withheld for every $3 earned above that amount. This higher limit applies only to earnings received before the month in which the person reaches full retirement age.
Both thresholds are expected to increase for 2027.
The earnings test does not permanently eliminate the withheld benefits. Instead, when a beneficiary reaches full retirement age, Social Security recalculates the benefit to account for months in which benefits were withheld because of the earnings test.
This means working beneficiaries should distinguish between a temporary withholding of benefits and a permanent reduction in their Social Security entitlement.
Timing
October 14, 2026, is the date beneficiaries and workers should watch for the official 2027 figures.
The announcement is expected to provide the year’s updated COLA, taxable maximum, earnings requirement for Social Security credits and retirement earnings test limits.
These numbers affect different groups in different ways. The COLA is particularly relevant to current beneficiaries, while the taxable maximum is more significant for higher-earning workers. The credit threshold matters to people building eligibility, and the earnings test is relevant to beneficiaries who claim Social Security while continuing to work before full retirement age.
The October announcement therefore provides more than one headline figure. Taken together, the changes will show how several important Social Security rules and thresholds are scheduled to operate in 2027.
For anyone planning retirement, continuing to work after claiming benefits or estimating future Social Security income, the official SSA figures are the numbers to use once they are released.