Retirement planning involves several important financial decisions, but few have consequences as long-lasting as choosing when to claim Social Security. For millions of Americans, these monthly payments provide a foundation for retirement income. While eligible workers can begin collecting benefits at age 62, doing so before full retirement age can permanently reduce the amount they receive each month.
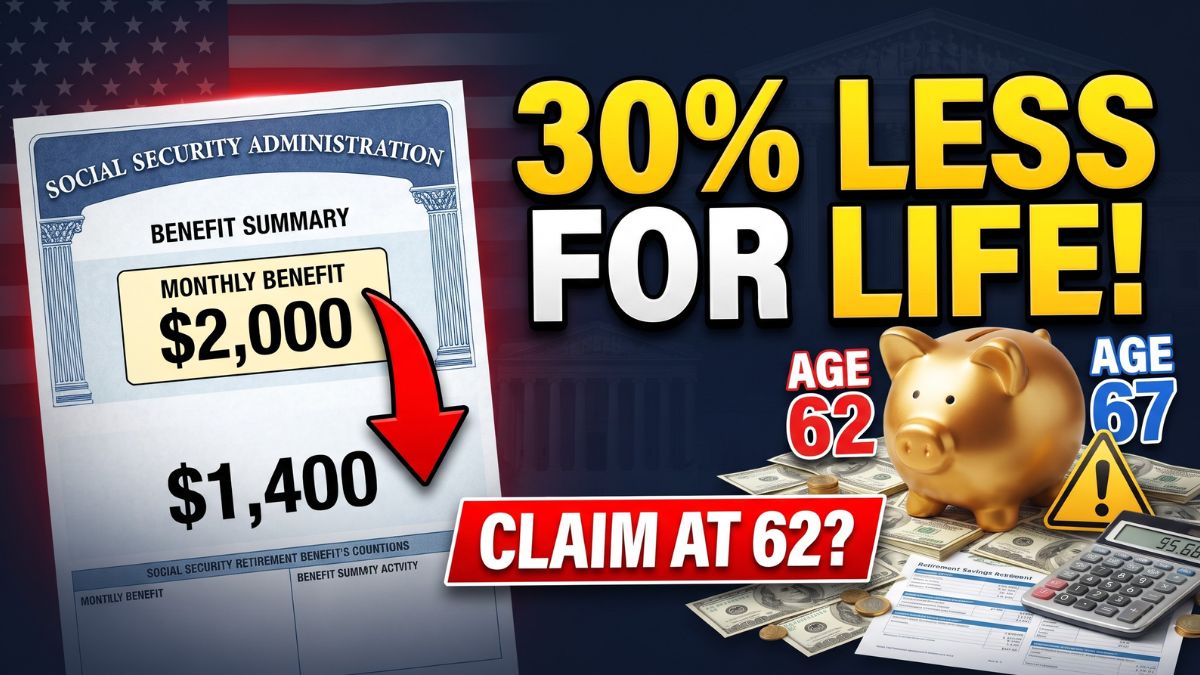
For someone whose full retirement age is 67, claiming benefits at 62 can result in a reduction of approximately 30%. That difference can become increasingly important as retirement progresses, particularly if personal savings decline, pension income becomes insufficient, or healthcare expenses increase.
The decision is not always straightforward. Some retirees have enough savings and other income sources to delay Social Security. Others may face unemployment, health problems, or financial difficulties that make early filing necessary.
Knowing how early claiming affects monthly payments, survivor benefits, and long-term retirement income can help individuals make a more informed decision.
Reductions
Social Security retirement benefits are calculated using a worker’s earnings history and the age at which benefits begin. Although eligible individuals can generally claim retirement benefits at 62, filing before full retirement age results in a permanent reduction.
For people born in 1960 or later, full retirement age is 67. Someone in this group who begins collecting benefits at 62 generally receives approximately 70% of their full retirement benefit.
Consider a hypothetical retiree named John. Based on his earnings record, his estimated Social Security benefit at age 67 is $2,000 per month. If he claims at 62, his monthly payment would be approximately $1,400.
That represents a difference of $600 every month, or $7,200 annually.
Initially, the reduction might not appear especially concerning. John has personal savings and a small pension, so he believes the additional income from Social Security will make retirement more comfortable.
However, retirement can last 25 or 30 years. Savings may gradually decline, unexpected expenses can arise, and other income sources may not provide the same level of financial support throughout retirement.
If John’s pension is relatively small and his savings eventually run low, his reduced Social Security payment could become an important financial limitation.
This is why the claiming decision should be evaluated over the entire retirement period rather than based only on immediate financial needs.
Timing
The difference between claiming at 62 and waiting until full retirement age can be substantial. The following example illustrates how filing age affects an estimated $2,000 monthly benefit at age 67.
| Claiming age | Monthly benefit | Reduction |
|---|---|---|
| 62 | $1,400 | 30% |
| 63 | $1,500 | 25% |
| 64 | $1,600 | 20% |
| 65 | $1,733 | 13.3% |
| 66 | $1,867 | 6.7% |
| 67 | $2,000 | 0% |
These figures are approximate illustrations. Actual Social Security payments depend on birth year, earnings history, and individual claiming circumstances.
Waiting beyond full retirement age can increase monthly benefits further. Eligible workers generally earn delayed retirement credits for postponing benefits until age 70.
For people born in 1943 or later, these credits generally increase retirement benefits by 8% for each full year of delay after full retirement age.
For someone with a full retirement age of 67, waiting until 70 can increase the retirement benefit by approximately 24%, before applicable cost-of-living adjustments.
However, delaying also means giving up several years of potential payments. Therefore, retirees should compare the benefits of waiting with their financial needs, health, and expected retirement expenses.
The Social Security Administration provides detailed information through its official Retirement Benefits page.
Circumstances
Claiming Social Security at 62 is not necessarily the wrong decision. Some people simply do not have enough financial resources to wait until full retirement age.
Consider someone who loses a job at 62 and struggles to find another position. If that individual has limited emergency savings, no pension, and ongoing household expenses, Social Security may become an essential source of income.
Beginning benefits early could help cover housing, groceries, utilities, insurance, and other necessities without relying heavily on credit cards or withdrawing investments during unfavorable market conditions.
Health is another important consideration. Someone with serious medical conditions or a shorter expected retirement period may prefer to receive benefits earlier rather than postpone payments.
On the other hand, individuals who remain healthy, have sufficient savings, and can continue working may have more flexibility to delay filing.
The decision should also account for employment income. Some people choose part-time work after leaving their primary careers, allowing them to meet expenses without immediately claiming Social Security.
However, people receiving benefits before full retirement age should understand the annual earnings test. Wages and self-employment income above the applicable limit can result in temporary benefit withholding.
Spouses
Early Social Security claiming can also affect household retirement planning, particularly when one spouse has earned considerably more than the other.
Survivor benefits are an important consideration for married couples. If the higher-earning spouse passes away, an eligible surviving spouse may receive benefits based on the deceased worker’s earnings record.
The amount depends on several factors, including the worker’s claiming history and the survivor’s age when benefits begin.
For example, imagine a married couple in which one partner has a substantially higher Social Security benefit and the other has a limited earnings history.
If the higher-earning spouse claims early, the resulting reduction may affect the survivor benefit available under applicable Social Security rules.
This can be particularly important when the surviving spouse is younger and may need retirement income for many additional years.
Couples should therefore evaluate their combined retirement income, individual earnings histories, and potential survivor benefits before deciding when to file.
Official eligibility information is available through the Social Security Administration’s Survivors Benefits page.
Inflation
Inflation is another factor that deserves attention when choosing a Social Security claiming age.
Retirement expenses rarely remain unchanged. Housing, groceries, transportation, insurance, and medical services can become more expensive over time.
Social Security addresses some of this pressure through annual cost-of-living adjustments, commonly called COLAs.
These adjustments are intended to help benefits maintain purchasing power as consumer prices change.
However, the starting benefit amount still matters. When someone claims early and receives a permanently reduced payment, future cost-of-living increases generally apply to that lower benefit.
For example, consider two retirees receiving different monthly payments.
| Monthly benefit | 3% COLA | New monthly benefit |
|---|---|---|
| $1,400 | $42 | $1,442 |
| $2,000 | $60 | $2,060 |
Both retirees receive the same percentage increase, but the person starting with the larger benefit receives a greater dollar increase.
Over many years, the difference can affect how comfortably retirees manage rising expenses.
Historical adjustments and official announcements are available through the Social Security Administration’s COLA page.
Planning
Before filing for Social Security, individuals should review their complete financial situation. Comparing monthly payments is useful, but retirement planning also requires understanding how different income sources will work together.
Several steps can help:
1. Review earnings records: Check your Social Security statement to ensure your reported earnings are accurate.
2. Compare filing ages: Examine estimated payments at 62, 67, and 70 to understand the financial differences.
3. Evaluate savings: Determine whether retirement accounts and other investments can support expenses while you delay benefits.
4. Consider healthcare costs: Account for insurance premiums, prescriptions, medical appointments, and unexpected expenses.
5. Review pension income: Understand whether your pension provides lifetime payments and whether it includes inflation adjustments or survivor benefits.
6. Consider your spouse: Evaluate how your claiming decision could affect household income and potential survivor benefits.
7. Prepare a withdrawal strategy: Decide how much money you can reasonably withdraw from retirement accounts without creating unnecessary financial pressure.
This final point is particularly important because building a retirement portfolio and managing withdrawals from one are different financial challenges.
During working years, investors generally focus on saving money, contributing to retirement accounts, and growing investments. After retirement, the priority shifts toward generating dependable income while managing market risk, inflation, and longevity.
A portfolio that performs well during the accumulation years may require a different strategy once withdrawals begin.
Fisher Investments offers a resource called The Definitive Guide to Retirement Income, which discusses retirement expenses, income sources, and withdrawal planning. Readers interested in these subjects can explore the retirement income guide.
Retirees should also review their estimated payments through the official my Social Security account. This allows eligible individuals to examine their earnings records and available benefit estimates.
Decisions
There is no universal claiming age that guarantees the best financial outcome for everyone. Claiming at 62 may be appropriate for someone facing unemployment, limited savings, or significant health concerns. Waiting until full retirement age or beyond may provide greater long-term income for individuals who can afford to postpone benefits.
The important consideration is whether receiving money earlier is worth accepting a permanently lower monthly payment.
Retirees should also remember that pensions, savings, and investment income may not remain sufficient throughout retirement. A larger Social Security benefit can provide a more dependable income foundation during later years, particularly when other financial resources become limited.
Ultimately, the decision should reflect personal circumstances, expected expenses, health, household income, and the financial needs of a spouse. Knowing these factors before filing can help retirees avoid unexpected income limitations and develop a retirement strategy that remains practical over time.