Millions of Americans receiving Social Security benefits are watching the latest forecasts for the 2027 cost-of-living adjustment, or COLA. The annual adjustment is designed to help benefits keep pace with changes in consumer prices.
The official 2027 COLA has not yet been announced. The Social Security Administration is expected to release the figure in October after the inflation data needed for the calculation becomes available.
Current forecasts point to an increase in the mid-3% range. Estimates can still move before the official announcement because the COLA calculation depends on inflation readings from three specific months.
Estimate
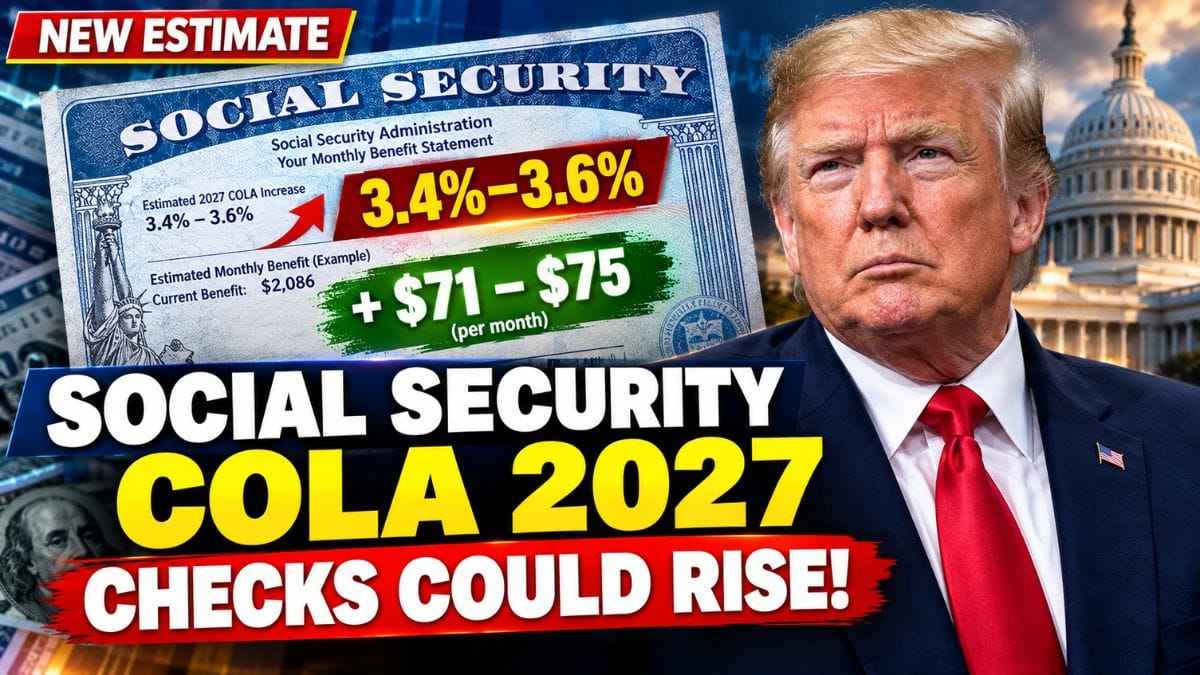
Recent projections put the potential 2027 Social Security COLA at roughly 3.4% to 3.6%.
Mary Johnson, an independent Social Security analyst, has estimated a 3.4% increase, while The Senior Citizens League has projected a 3.6% adjustment. Other forecasts have generally clustered around the same range.
The estimates are not official. They can change as new inflation data is released.
For comparison, Social Security benefits increased by 2.8% in 2026. If the current forecasts prove accurate, the 2027 adjustment would therefore be larger than this year’s increase.
The latest projections from AARP and The Senior Citizens League provide additional context on the current outlook.
Increase
A COLA percentage applies to a person’s existing Social Security benefit. That means two beneficiaries can receive different dollar increases even when they receive the same percentage adjustment.
For example, if a beneficiary receives $2,086 per month, a 3.4% increase would add about $71 per month. A 3.6% increase would add roughly $75 per month.
| Current monthly benefit | 3.4% increase | 3.6% increase |
|---|---|---|
| $1,500 | $51.00 | $54.00 |
| $2,000 | $68.00 | $72.00 |
| $2,086 | $70.92 | $75.10 |
| $2,500 | $85.00 | $90.00 |
| $3,000 | $102.00 | $108.00 |
These are illustrations rather than predictions of individual payments. The actual increase depends on the beneficiary’s current benefit amount and the final COLA.
Calculation
The Social Security COLA is tied to the Consumer Price Index for Urban Wage Earners and Clerical Workers, commonly called CPI-W.
Under the current formula, Social Security uses the average CPI-W readings for July, August and September. Those figures are compared with the corresponding third-quarter average from the previous year.
If the new three-month average is higher, the percentage difference determines the COLA for the following year.
The Social Security Administration’s official CPI-W information explains the calculation and provides the historical data used in determining annual adjustments.
This is why analysts pay close attention to each new inflation report during the summer and early fall. One month’s inflation reading can change the assumptions behind a forecast, while the final September data can determine the official calculation.
Announcement
The official 2027 COLA is expected to be announced on Wednesday, Oct. 14.
Until that announcement, estimates should be treated as forecasts rather than confirmed benefit increases.
Once the SSA releases the official percentage, beneficiaries can calculate their approximate new gross monthly benefit by multiplying their current benefit by the COLA percentage.
For example, a 3.5% COLA would turn a $2,000 monthly benefit into approximately $2,070 before considering any deductions.
The final amount deposited into a bank account can be different from the gross benefit because Medicare premiums, taxes and other deductions can affect the net payment.
Inflation
The reason COLA forecasts receive so much attention is that inflation affects household budgets in many ways.
Retirees may face higher costs for groceries, housing, utilities, transportation, insurance and medical care. A percentage increase in Social Security benefits does not necessarily match the changes in every individual’s expenses.
For example, someone who spends a larger share of their income on healthcare may experience a different financial impact from the same COLA as another beneficiary with lower medical expenses.
That makes the COLA an important part of retirement budgeting, but not a complete measure of how a beneficiary’s purchasing power changes.
Recent inflation data have helped push current 2027 forecasts into the mid-3% range. However, the final calculation will depend on the CPI-W figures used by Social Security.
Calendar
The SSA has also published its 2027 Social Security payment schedule.
Social Security payments are generally distributed according to the beneficiary’s birth date and other factors. The regular Wednesday schedule is:
| Payment timing | Beneficiaries generally included |
|---|---|
| Second Wednesday | Birthdays from the 1st through 10th |
| Third Wednesday | Birthdays from the 11th through 20th |
| Fourth Wednesday | Birthdays from the 21st through 31st |
| Third day of month | Certain beneficiaries who started receiving benefits before May 1997 |
Payments can be adjusted when a scheduled payment date falls on a weekend or federal holiday.
The payment calendar is separate from the COLA calculation. The COLA determines how much a benefit increases, while the payment schedule determines when that benefit is generally delivered.
Outlook
For now, a 3.4% to 3.6% Social Security COLA is best viewed as an estimate rather than a confirmed increase. The final number will depend on the inflation data used in the official calculation.
If the adjustment lands in that range, a beneficiary receiving about $2,086 per month could see an increase of roughly $71 to $75 per month before deductions. People receiving larger or smaller benefits would see different dollar increases.
The official announcement will settle the 2027 COLA question. Until then, beneficiaries can use the latest projections to prepare different household budget scenarios, while keeping in mind that forecasts can change before the final figure is released.