Benefit claimants may face additional checks on certain bank account information under new powers available to the Department for Work and Pensions (DWP).
The measures cover some people receiving Universal Credit, Pension Credit and Employment and Support Allowance (ESA). Banks and other financial institutions can be required to check whether accounts connected to benefit recipients meet specific eligibility indicators.
The checks are part of the Eligibility Verification Measure (EVM). Under the system, financial institutions receive an Eligibility Verification Notice (EVN) setting out the criteria they are required to examine.
The exact indicators being used are not publicly disclosed. The Government has said that publishing detailed criteria could make it easier for people attempting to commit benefit fraud to avoid detection.
However, the official Code of Practice gives examples of the circumstances that could be relevant.
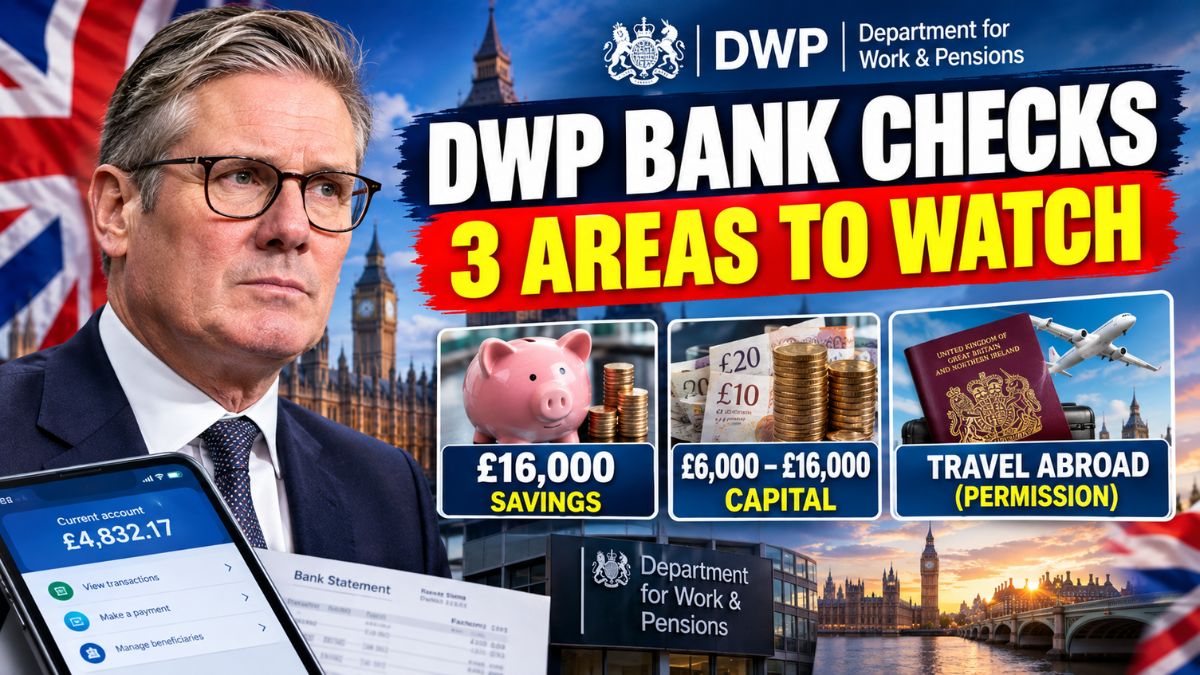
Savings
One of the main areas concerns the amount of capital a claimant holds.
For Universal Credit, people with more than £16,000 in capital are generally not eligible for the benefit, although certain types of capital can be treated differently under the rules.
The rules also take account of capital between £6,000 and £16,000. In this range, Universal Credit can be reduced depending on the amount of capital held.
As a result, information indicating that someone may have capital within or above these ranges could be relevant to an eligibility verification check.
Importantly, the presence of a particular amount of money in an account does not by itself establish that a claimant has broken the rules. Benefit calculations can involve exemptions and disregards, meaning some money may not count as capital in the usual way.
Travel
Time spent outside the UK is another area that can potentially be relevant.
Benefit rules can restrict how long someone may be able to remain abroad while continuing to receive certain benefits. The applicable conditions vary depending on the benefit and the individual’s circumstances.
The Code of Practice indicates that eligibility indicators may be used where there are signs that a claimant could have spent longer abroad than permitted.
Again, an indicator is not the same as a final finding. If a person’s information produces a potential match, further checks may be needed to establish what actually happened and whether the claimant remained entitled to their benefit.
There can be legitimate reasons for information appearing inconsistent with the relevant rules, so the initial flag is only part of the verification process.
Checks
The new system does not give the DWP unrestricted access to people’s banking activity.
When an EVN is issued, financial institutions are restricted in the information they can provide. The regulations prevent banks from supplying transaction details that reveal what a person purchased or where they spent their money.
The type of personal and sensitive information that can be requested is also restricted.
Instead, banks use information they already hold to identify accounts that meet the criteria specified in an EVN. If an account matches, only permitted information can be supplied to the DWP.
This distinction is important because the system is designed around eligibility verification rather than giving the department a complete record of an individual’s spending.
Indicators
The Government has not published every specific indicator that could be used in the verification process.
According to the Code of Practice, however, three broad areas are particularly relevant:
| Area | Why it may matter |
|---|---|
| Capital above £16,000 | This can affect Universal Credit eligibility |
| Capital between £6,000 and £16,000 | This can reduce Universal Credit payments |
| Extended time abroad | Benefit rules can limit periods spent outside the UK |
These categories should not be interpreted as automatic evidence of wrongdoing. They are circumstances that may lead to information being considered as part of an eligibility check.
Protection
There are restrictions governing the information that banks can provide to the DWP.
The regulations limit the information that may be disclosed following an EVN, including restrictions concerning transaction information and certain categories of personal data.
This means the new powers are not equivalent to unrestricted access to a claimant’s bank statements.
The Government has said the wider system is intended to help identify fraud and error while operating within rules governing how financial information is obtained and used.
The powers form part of the Public Authorities (Fraud, Error and Recovery) Act 2025.
Investigation
A bank account being identified through the verification process does not automatically mean that benefits will be stopped.
The DWP has indicated that a match on its own does not establish that a claimant has been overpaid or is no longer eligible. Further investigation and verification would be required before a decision is made.
There may also be legitimate explanations for information that initially appears inconsistent with benefit rules.
For example, a claimant could appear to have savings above a relevant threshold, while some of the money may fall within a category that is legally disregarded when calculating entitlement.
Claimants
For people receiving Universal Credit, Pension Credit or ESA, the changes make it important to understand how eligibility rules apply to their individual circumstances.
Savings, other forms of capital and time spent abroad can all be relevant depending on the benefit being claimed and the rules that apply.
At the same time, claimants should not assume that an account being flagged automatically means their payments will be suspended or withdrawn. The verification process is intended to identify cases that may require further examination.
The new banking checks therefore represent an additional verification mechanism rather than an automatic penalty system. The DWP must still establish the relevant facts and determine whether a person’s benefit entitlement has actually been affected before taking further action.