People receiving certain benefits have been warned that information linked to their bank accounts could lead to additional checks by the Department for Work and Pensions (DWP).
New rules allow the DWP to require banks and other financial institutions to check accounts belonging to people receiving certain benefits against specific eligibility indicators. The measure applies to benefits including Universal Credit, Pension Credit and Employment and Support Allowance (ESA).
The checks are being introduced through the new Eligibility Verification Measure (EVM). Under the system, banks can receive an Eligibility Verification Notice (EVN) setting out the criteria they need to check.
The Government has said the exact indicators used by the DWP will not be made public. This is intended to prevent people committing fraud from changing their behaviour to avoid detection. However, the official Code of Practice provides examples of the types of information that may be relevant.
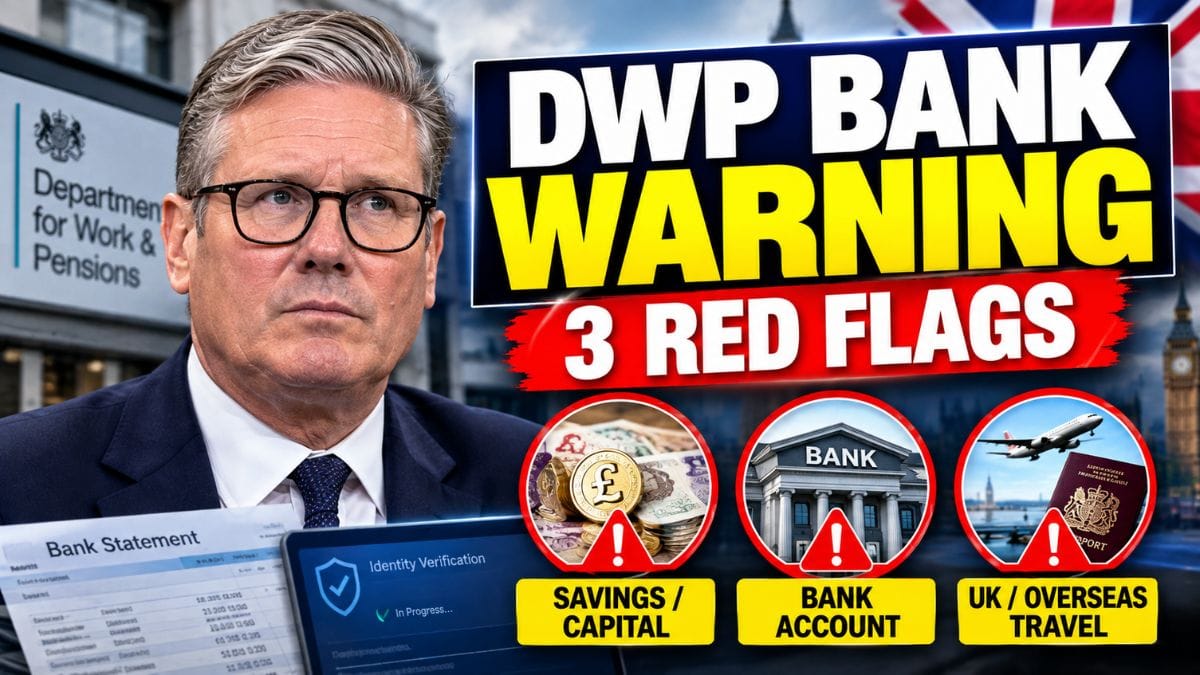
Savings
One of the main areas that could trigger a check is the amount of savings or capital held by a claimant.
For Universal Credit, people with more than £16,000 in capital are normally not eligible for the benefit, although there are some exceptions to this rule.
The DWP may also ask banks to identify people with capital between £6,000 and £16,000. This is because having capital within this range can affect the amount of Universal Credit a person receives.
The presence of savings above a particular threshold does not automatically mean that someone is incorrectly claiming benefits. Some types of capital can be disregarded when entitlement is calculated, depending on an individual’s circumstances.
Capital
The second area relates to capital that falls within the range where it can affect Universal Credit payments.
Universal Credit is means-tested, meaning a claimant’s financial circumstances can affect their entitlement. Capital between £6,000 and £16,000 can therefore be relevant when the DWP assesses a claim.
If information held by a bank indicates that a claimant may have capital within this range, the account could potentially be identified through an EVN.
However, the information would not by itself prove that a claimant had received the wrong amount of benefit. The DWP would need to carry out further checks before making a decision.
There can also be legitimate explanations for apparent discrepancies between bank information and benefit records.
Overseas
The third area highlighted by the rules concerns time spent outside the UK.
The Code of Practice says eligibility indicators may be used where there are indications that someone receiving a relevant benefit may have spent more time overseas than the benefit rules allow.
Different benefits have their own rules covering temporary absences and residence requirements. As a result, spending time outside the UK does not automatically mean that someone is no longer entitled to benefits.
Instead, an indication identified through the new system could lead to further checks by the DWP.
Checks
A bank account being flagged under the new system does not automatically mean that a person’s benefits will be stopped or reduced.
The DWP has stated that an account being identified through an eligibility indicator would not, on its own, establish that a claimant had been overpaid or was no longer entitled to their benefit.
Further investigation would be required before the department could make a decision about a person’s entitlement.
This distinction is important because financial information can sometimes appear inconsistent with benefit rules even when a claimant is following the rules. For example, the Code of Practice gives the example of someone appearing to have savings above a normal capital limit when some of that money is legally disregarded when calculating their entitlement.
Privacy
The new powers also do not give the DWP unrestricted access to people’s bank accounts.
Banks cannot provide transaction information showing what someone has purchased or where they have spent their money in response to an EVN. The rules also limit the categories of personal and sensitive information that can be requested.
Instead, financial institutions use information they already hold to identify accounts that match the criteria contained in an EVN.
Where an account is identified, limited information can then be provided to the DWP to help establish whether there may be an issue with benefit entitlement.
Purpose
The Government says the measure is designed to help tackle fraud and error within the benefits system while providing safeguards around the collection and use of financial information.
The new powers form part of the Public Authorities (Fraud, Error and Recovery) Act 2025.
For claimants, the three main areas highlighted by the rules are capital above relevant thresholds, capital between £6,000 and £16,000 where it affects Universal Credit, and indications that someone may have spent an extended period outside the UK.
Being identified through one of these indicators does not automatically mean that benefits will be reduced or stopped. Further checks are required before the DWP can make a decision about a claimant’s entitlement.