The Department for Work and Pensions (DWP) has opened a consultation on plans to tackle the growing number of small, inactive pension pots held by savers across the defined contribution pension market.
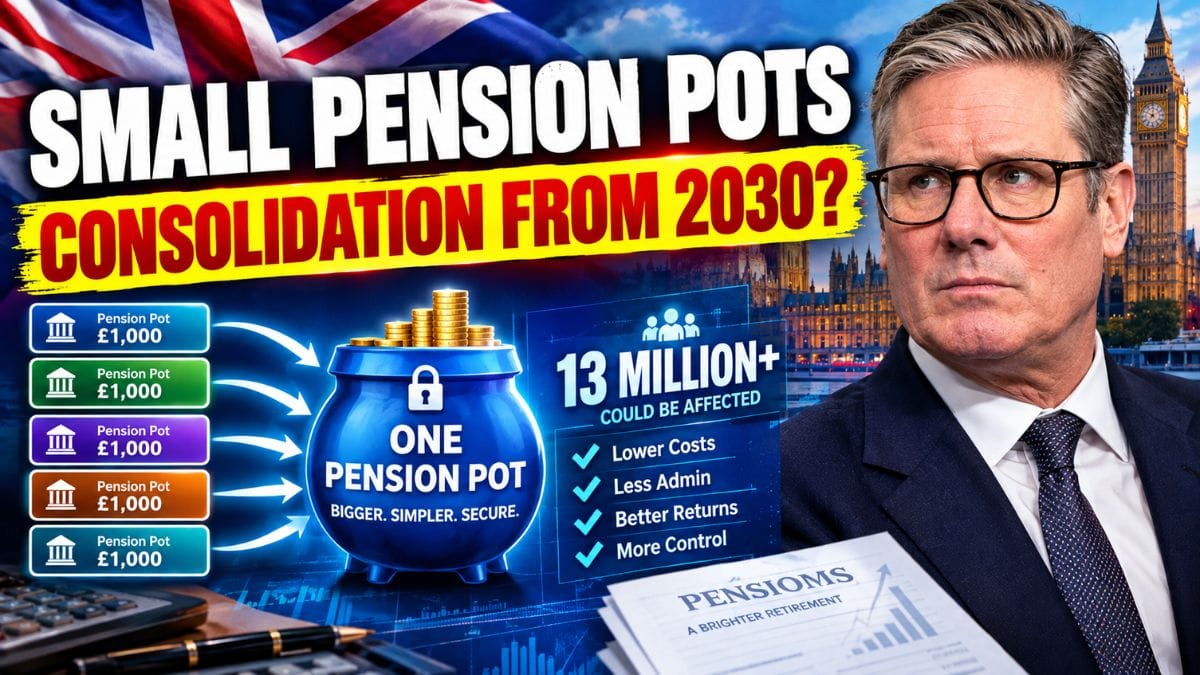
The government says more than 13 million deferred pension pots are currently worth £1,000 or less, with the number increasing by around 1 million each year.
The proposed reforms would create a system for transferring eligible small pension pots into authorised consolidator schemes. The government expects the new arrangements to become operational from 2030.
Problem
Small pension pots can accumulate when people change jobs and leave previous workplace pension arrangements behind.
Over a working life, someone may build up several pension pots with different providers. While each pot may be relatively small, managing millions of separate accounts creates additional administrative work for pension providers.
The DWP estimates that the administration of these small pots costs pension providers around £240 million each year. Those costs can ultimately be reflected in charges and expenses borne by pension savers.
The consultation is intended to address that issue by creating a more structured approach to consolidating eligible pots.
Proposal
Under the proposals, pension pots worth £1,000 or less that have been inactive for at least 12 months could be transferred into consolidator schemes.
The approach is designed to reduce the number of small, dormant pension accounts while bringing them together in larger arrangements.
The proposed threshold and inactivity period are important because not every pension pot would automatically be included.
The consultation is also examining how consolidator schemes would operate, including their authorisation, governance and the systems needed to transfer pension assets and information between providers.
Timeline
The government has set an ambition for small-pension-pot consolidation to become operational from 2030.
That means there is still several years for the proposed framework to be developed, consulted on and implemented.
Pensions Minister Torsten Bell said the government wants to create a system with fewer, larger pots that are easier to manage and less costly to administer.
The current consultation is therefore an important stage in determining how the policy would work in practice.
Members
The government says the interests of pension members should remain central to the reforms.
Consolidating pension pots is not simply a matter of moving money from one account to another. The receiving arrangements will need to meet the requirements established under the eventual framework.
Industry representatives have also highlighted the importance of ensuring that savers are transferred into arrangements that provide appropriate governance and value.
David Pye, head of client development at Broadstone, said consolidation should focus on member outcomes rather than simply transferring assets into larger schemes.
He also pointed to practical issues that still need to be addressed, including authorisation, data matching and communication with members.
Operations
The scale of the proposed changes means the operational requirements could be substantial.
With more than 13 million existing deferred pots valued at £1,000 or less, and the number increasing by approximately 1 million annually, pension providers will need systems capable of identifying eligible accounts and matching them with the appropriate receiving arrangements.
Data accuracy will be particularly important.
Providers will need to establish which pension pots meet the relevant criteria, identify the correct member records and ensure that transfers take place under the applicable rules.
Communication will also matter because savers need to understand what is happening to their pension and where their money is being transferred.
Technology
The consultation also considers the digital infrastructure that would support the consolidation model.
Maurice Titley, commercial director for data and dashboards at Lumera, described small-pot consolidation as a major operational exercise for the pensions industry.
He said a proposed federated delivery model could allow pension schemes to continue handling data exchanges, matching and transfers through scheme-led processes while operating within common standards and governance arrangements.
Such an approach could help providers work within a consistent framework without requiring every element of the process to be handled through a single central system.
The consultation gives the industry an opportunity to examine how these technical and operational arrangements could work at scale.
Costs
The government’s case for reform is partly based on reducing unnecessary administration.
When large numbers of small pension accounts remain open, providers can incur costs associated with maintaining records, communicating with members and administering individual pots.
Bringing eligible pots together could reduce duplication and make pension administration more efficient.
However, the eventual impact on savers will depend on the final rules, including how consolidator schemes are authorised, what charges they can impose and how member protections are applied.
The consultation is intended to help resolve those details before the proposed system is introduced.
Outlook
The proposed consolidation of small pension pots could change how many workplace pension accounts are managed in the UK.
For savers, the main issue will be how the final framework protects pension value while reducing administrative duplication. For providers, the challenge will be building systems capable of identifying, matching and transferring potentially millions of eligible pots.
The DWP is now seeking views on the proposals, with the government aiming to have the consolidation system operating from 2030. The consultation process will help determine the detailed rules, governance arrangements and technology needed to make that timetable possible.