Social Security beneficiaries are expected to receive higher monthly payments in 2027 following a reported 3.6% cost-of-living adjustment (COLA). The increase would provide additional income to millions of retired Americans, disabled workers, and eligible recipients of other Social Security benefits as households continue to manage the cost of everyday expenses.
According to the supplied report, the adjustment would increase average retirement benefits by approximately $75 per month. The change would apply to eligible benefits beginning in January 2027 and would affect retirement, survivor, and disability benefits under Social Security, along with Supplemental Security Income (SSI), subject to the relevant program rules.
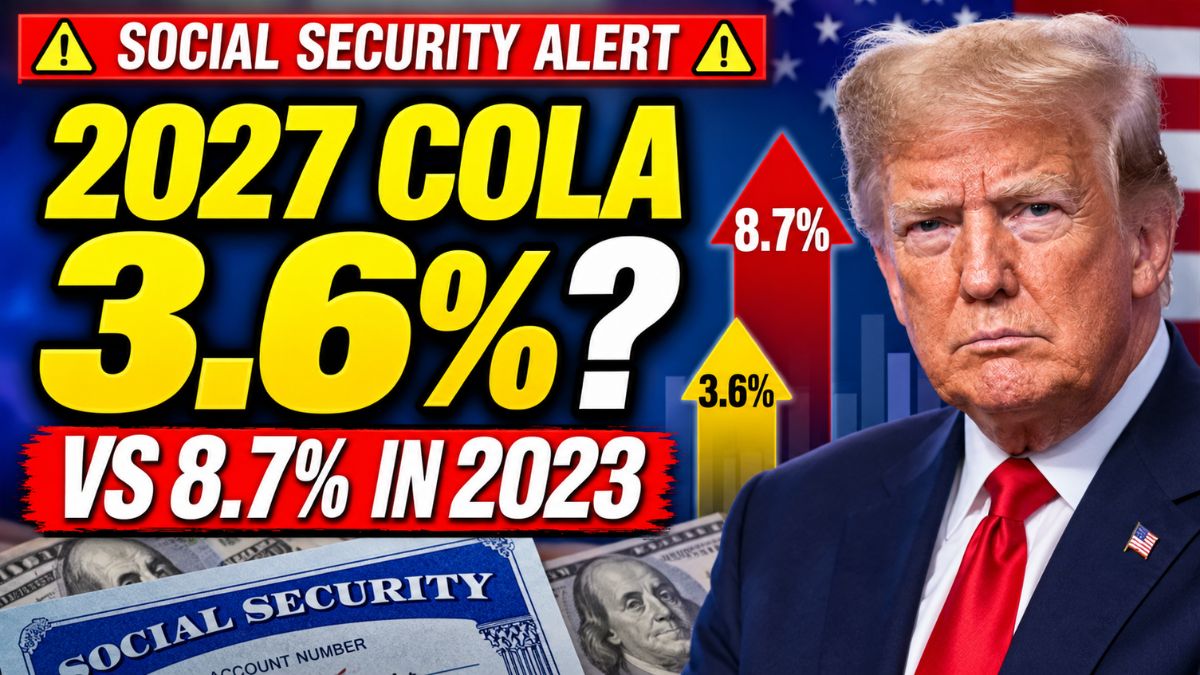
The reported 3.6% increase would also represent the largest annual COLA since 2023, when Social Security benefits rose by 8.7% following a period of elevated inflation. Although the 2027 adjustment would provide additional financial support, its effect on household budgets will depend on benefit amounts, deductions, and changes in the prices of essential goods and services.
For retirees who rely on Social Security as a primary source of income, understanding the adjustment is important for planning monthly expenses and evaluating how much purchasing power the increase may provide.
Editorial note: The 3.6% COLA announcement and 2027 payment figures below are based on the supplied report. Confirm the announcement and exact figures against official Social Security Administration sources before publication.
Increase
The reported 3.6% cost-of-living adjustment is intended to help Social Security beneficiaries maintain their purchasing power as consumer prices change. Rather than providing a one-time payment, a COLA generally increases eligible monthly benefits on an ongoing basis.
According to the report, approximately 76 million Americans would be affected by the 2027 adjustment. These beneficiaries include retired workers, eligible family members, survivors, and people receiving disability benefits. SSI recipients may also receive an adjustment under the program’s applicable rules.
For the average retired worker, the reported increase of approximately $75 per month would amount to roughly $900 over a full year. The actual increase would vary according to the individual’s existing benefit amount.
For example, a beneficiary receiving $1,500 per month would receive a smaller dollar increase than someone receiving $3,000, even if both received the same percentage adjustment.
The additional income could help households cover recurring expenses, including groceries, utility bills, transportation, and healthcare. However, the increase does not guarantee that every beneficiary will experience an improvement in their financial position.
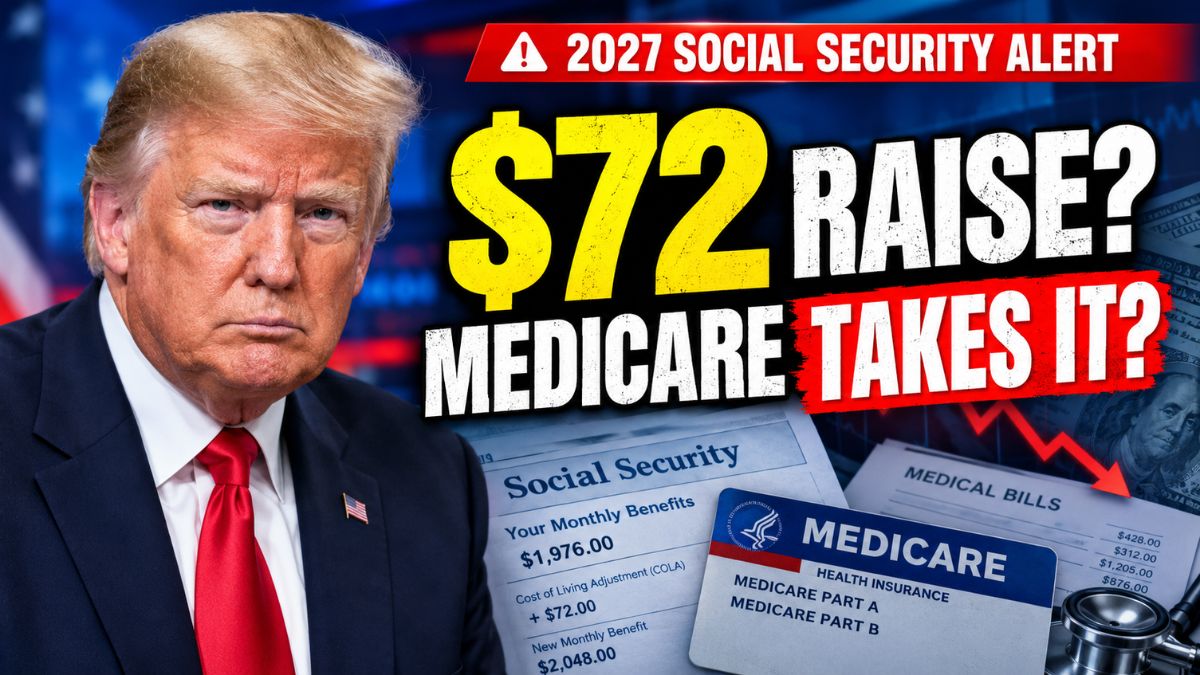
Medicare premiums, tax withholding, and other applicable deductions can affect the final amount deposited into a beneficiary’s account.
Payments
A 3.6% COLA would increase benefits in proportion to the amount currently received. The following table illustrates how the reported adjustment could affect different monthly payment levels.
| Current Monthly Benefit | Estimated Increase | New Monthly Benefit |
|---|---|---|
| $1,000 | $36 | $1,036 |
| $1,500 | $54 | $1,554 |
| $2,000 | $72 | $2,072 |
| $2,500 | $90 | $2,590 |
| $3,000 | $108 | $3,108 |
These figures are illustrative estimates calculated by applying 3.6% to each benefit amount. They do not represent individual payment determinations from the Social Security Administration.
For a beneficiary receiving $2,000 per month, the estimated increase would be $72, bringing the monthly benefit to $2,072 before applicable deductions. Over 12 months, that would represent an additional $864 if the full increase applied throughout the year.
A beneficiary receiving $3,000 per month would see an estimated increase of $108 monthly, or $1,296 over 12 months.
The examples show why the dollar value of a COLA can differ considerably between beneficiaries. A uniform percentage adjustment does not provide the same additional amount to everyone.
Calculation
The Social Security Administration traditionally calculates the annual COLA using the Consumer Price Index for Urban Wage Earners and Clerical Workers, known as CPI-W.
The calculation compares the average CPI-W for July, August, and September of the current year with the average for the same three months in the previous year. When the index rises, the resulting percentage change determines the annual adjustment under Social Security’s rules.
This method is designed to reflect changes in consumer prices and help prevent inflation from gradually reducing the purchasing power of Social Security payments.
The approach also means the COLA is based on a specific measurement period rather than the change in prices during an entire calendar year. Monthly inflation reports can provide context, but they do not independently determine the final adjustment.
Beneficiaries can review the official calculation method and annual adjustment information through the Social Security Administration’s COLA page.
The CPI-W methodology has also attracted criticism because its spending weights may not accurately reflect the financial circumstances of older Americans, particularly those with substantial medical or housing expenses.
History
The reported 3.6% adjustment would be higher than the COLAs introduced in each of the three preceding years, although it would remain below the exceptional increase recorded in 2023.
The annual adjustments cited in the supplied report are as follows:
| Year | Reported COLA |
|---|---|
| 2023 | 8.7% |
| 2024 | 3.2% |
| 2025 | 2.5% |
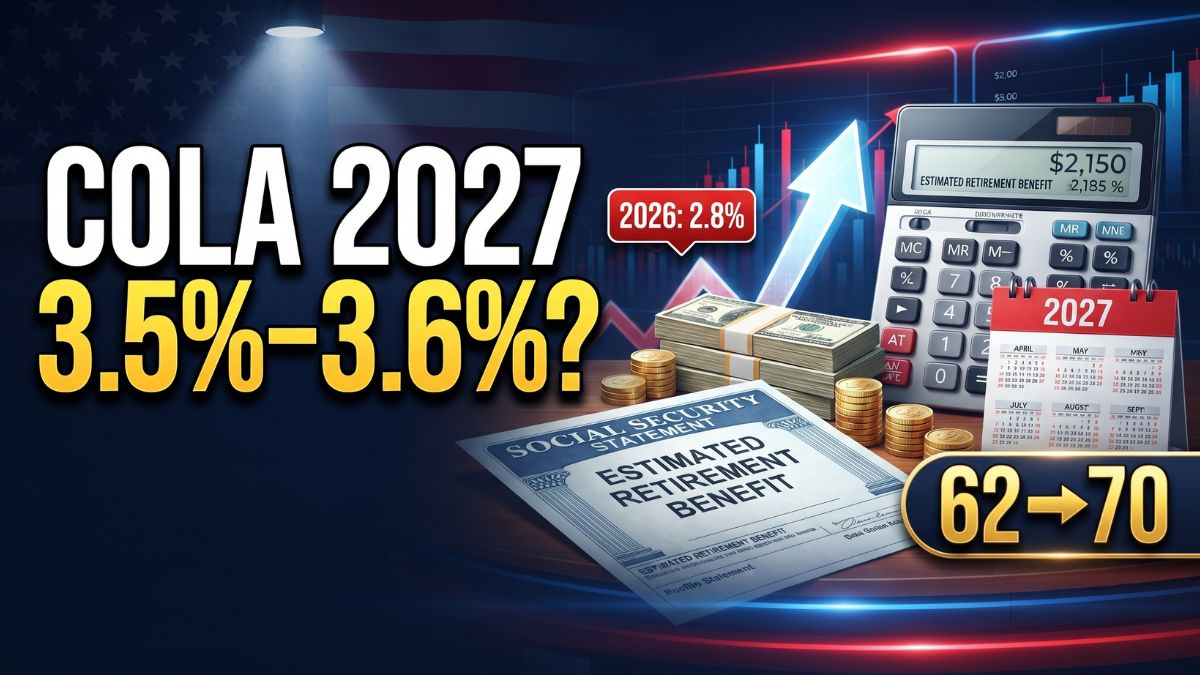
| 2026 | 2.8% |
| 2027 | 3.6% |
The 8.7% adjustment in 2023 followed a period of particularly high inflation. As inflation moderated, the annual adjustments became smaller in subsequent years.
The reported increase for 2027 would reflect renewed price pressures during the measurement period used for the adjustment. However, the COLA should not be interpreted as a direct forecast of inflation for the following year. It reflects changes in the index used for the calculation rather than guaranteeing that prices will rise at the same rate after the adjustment takes effect.
Historical comparisons can help beneficiaries understand how annual adjustments change over time, but the effect on an individual household depends on its spending patterns and financial circumstances.
Energy
Energy prices were identified in the supplied report as one factor contributing to the larger 2027 adjustment. Higher oil and gasoline prices can influence household budgets directly through fuel and heating expenses and indirectly through transportation and the cost of moving goods.
When energy prices rise, businesses may face higher operating and distribution costs. Some of those increases can eventually affect the prices consumers pay for food, household products, and other necessities.
For retirees living on fixed incomes, these changes can create additional financial pressure. Unlike many working households, retirees may have limited opportunities to increase their earnings when expenses rise.
The reported increase in energy costs was linked to disruptions associated with the Iran war and oil and gasoline supply chains. Energy prices can fluctuate considerably, however, and their contribution to overall inflation depends on the scale and duration of supply disruptions, demand, and other economic factors.
A higher COLA can help offset some of the additional expenses, but it cannot ensure that every beneficiary’s household costs will rise by less than their benefit.
Retirement
Social Security provides an important source of retirement income for millions of Americans. For some households, it supplements pensions, savings, and investment income. For others, it represents the majority or entirety of their regular income.
This difference matters when evaluating the impact of a COLA. Retirees with substantial savings or multiple income sources may have greater flexibility to absorb higher expenses. Those relying almost entirely on Social Security may need to allocate most of any increase toward essential bills.
The supplied report also cited concerns about retirement preparedness among older Americans, including the number of people who have no retirement savings. When households have limited financial reserves, changes in everyday expenses can have a significant effect on their ability to meet monthly obligations.
The adjustment may help cover a portion of rising costs, but it does not replace the need to consider housing expenses, healthcare needs, emergency savings, and other sources of retirement income.
People approaching retirement can review their projected benefits using the official my Social Security account portal. The portal provides access to individual Social Security information and can help eligible users review their benefit estimates and account details.
Distribution
Although the COLA is expressed as a percentage, the resulting dollar increase varies according to the benefit amount. This distinction is important when assessing how the adjustment affects beneficiaries across different income levels.
The Committee for a Responsible Federal Budget, cited in the supplied report, estimated that the 3.6% adjustment would increase average benefits by approximately $900 annually per retiree. The organization also noted that people receiving larger benefits could receive substantially greater dollar increases.
Higher Social Security benefits generally reflect factors such as a person’s earnings history and the age at which they claimed retirement benefits. As a result, beneficiaries do not all start with the same monthly payment.
A percentage-based adjustment increases existing benefits proportionally, so someone receiving a larger benefit generally receives a larger increase in dollar terms.
However, the size of the increase alone does not determine a person’s financial security. A retiree with a higher benefit may also have greater housing or healthcare expenses, while someone receiving a smaller payment may have access to other household income.
The most useful assessment considers both the additional benefit and the recipient’s overall financial situation.
Eligibility
The COLA generally applies automatically to eligible Social Security beneficiaries, meaning most recipients do not need to submit a separate application simply to receive the annual adjustment.
Retirement benefits, survivor benefits, and Social Security Disability Insurance are subject to the applicable Social Security adjustment rules. SSI benefits are also adjusted under their own program requirements.
Although the adjustment is automatic for eligible recipients, the timing and amount of payments may differ according to benefit type and individual circumstances.
Beneficiaries should also distinguish between Social Security retirement or disability benefits and other government assistance programs. Not every program uses the same calculation method, eligibility criteria, or payment schedule.
For information about benefit categories, eligibility requirements, and official announcements, recipients can consult the Social Security Administration’s official website.
Planning
Beneficiaries can prepare for the new benefit year by reviewing their household budgets and identifying how much they spend on essential expenses.
Housing, food, utilities, transportation, insurance, and medical costs are useful categories to examine. Comparing these expenses with previous months can help retirees determine whether price increases are reducing the value of their income.
It is also important to review the difference between gross benefits and take-home payments. Changes in Medicare premiums or other deductions may affect how much of the COLA reaches a beneficiary’s bank account.
Retirees with limited income may wish to investigate programs that help eligible households pay for food, healthcare, energy, or other essential services. Eligibility depends on the specific program and the individual’s circumstances.
Before making financial decisions based on a reported adjustment, beneficiaries should review their official notices and confirm their payment amounts through the Social Security Administration.
The reported 3.6% COLA for 2027 would provide an increase in monthly income for eligible beneficiaries if confirmed by the SSA. Its practical value will depend on existing benefit amounts, applicable deductions, and changes in household expenses. For retirees, understanding the calculation, checking official payment information, and planning around essential costs can help clarify what the adjustment means for their finances.