Americans who continue working after claiming Social Security retirement benefits may be able to earn more in 2027 without triggering the same benefit withholding rules that apply today. However, the amount they can earn before Social Security payments are affected depends on their age and whether they have reached full retirement age.
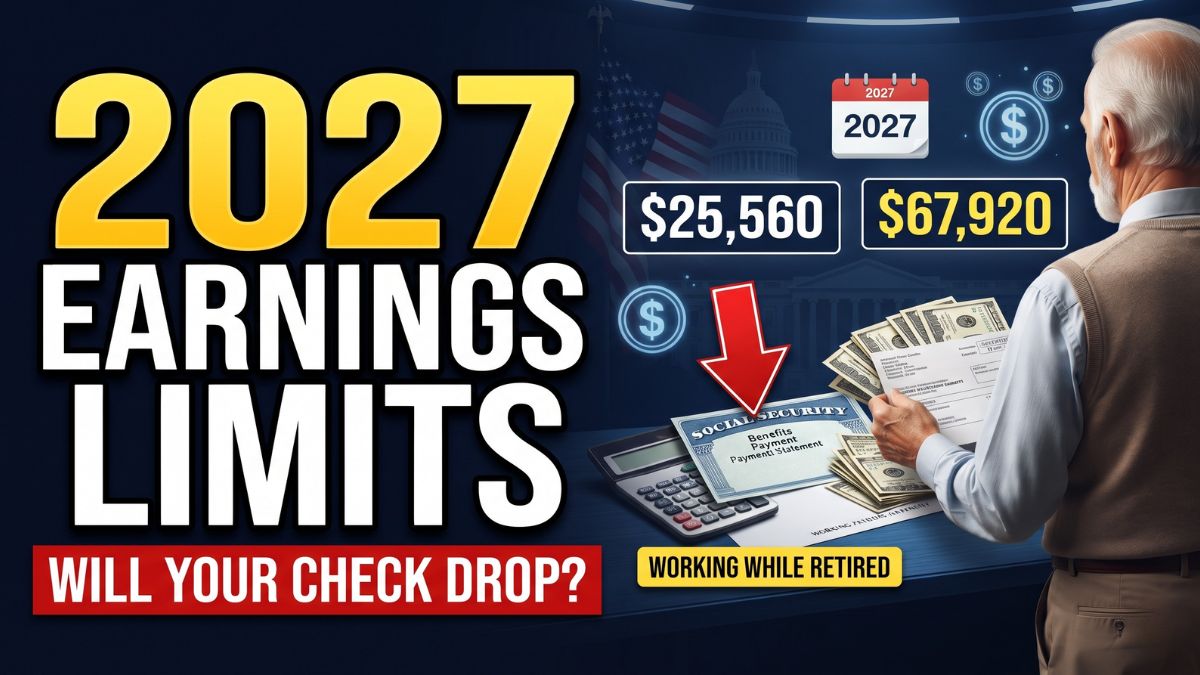
The annual earnings limits are scheduled to increase in 2027. For people who claim benefits before reaching full retirement age, the limit will rise to $25,560, up from $24,480 in 2026. Those who reach full retirement age during 2027 will have a higher limit of $67,920 for earnings received before the month they reach that age.
These rules matter for retirees who take part-time jobs, return to the workforce, or continue working while receiving benefits. Earning more than the applicable limit can lead to temporary withholding of Social Security payments, but it does not automatically end eligibility.
The key is knowing which earnings count, how much the Social Security Administration can withhold, and what changes once full retirement age is reached.
Limits
The Social Security earnings test applies to people receiving retirement benefits who have not yet reached full retirement age. The limits are reviewed periodically and can change from one year to the next.
For 2027, the annual limits are scheduled to be:
| Beneficiary’s situation | 2026 limit | 2027 limit |
|---|---|---|
| Below full retirement age for the entire year | $24,480 | $25,560 |
| Reaching full retirement age during the year | $65,160 | $67,920 |
The higher limit for people reaching full retirement age applies to earnings received before the month they reach that age. Once that month arrives, the earnings test no longer applies to their retirement benefits.
For example, a person who has claimed Social Security at age 64 and continues working throughout 2027 would generally be subject to the lower annual limit if they remain below full retirement age for the entire year. Someone turning 67 and reaching full retirement age during the year would be subject to the higher limit for the months before reaching that milestone.
These thresholds are different from the amount a person can earn while working after full retirement age. After reaching full retirement age, there is no earnings-based limit on Social Security retirement benefits.
Readers should confirm the applicable figures through the Social Security Administration’s official earnings test guidance, particularly when planning work arrangements or deciding whether to claim benefits.
Withholding
Exceeding the annual earnings limit does not mean the Social Security Administration takes away all your benefits. Instead, the agency withholds a portion of retirement benefits according to a set formula.
For people who remain below full retirement age throughout 2027, Social Security generally withholds $1 in benefits for every $2 earned above the annual limit of $25,560.
Consider a worker who receives retirement benefits and earns $30,000 in wages during 2027. The amount above the limit would be $4,440.
Under the standard earnings test, the calculation would be:
- Annual earnings: $30,000
- Earnings limit: $25,560
- Earnings above the limit: $4,440
- Potential benefits withheld: $2,220
The actual effect on monthly payments depends on the person’s benefit amount and the SSA’s withholding process. The calculation illustrates how the earnings test works, rather than guaranteeing that a particular month’s check will be reduced by a specific amount.
A different formula applies to people who reach full retirement age during 2027. For those beneficiaries, Social Security generally withholds $1 for every $3 earned above the higher limit of $67,920, counting only earnings received before the month full retirement age is reached.
This distinction can make a significant difference for people approaching full retirement age. A worker who earns more than the lower limit may still fall below the higher threshold applicable to someone reaching full retirement age during the year.
Adjustments
Benefits withheld under the earnings test are not necessarily lost permanently. Once a beneficiary reaches full retirement age, the Social Security Administration adjusts the retirement benefit to account for months in which payments were withheld, resulting in a higher monthly benefit than would otherwise apply.
This adjustment is important because the earnings test is designed to affect the timing of benefits, not simply to impose a permanent reduction for earning too much while working.
The adjustment is generally based on the months in which benefits were withheld or reduced because of the earnings test. It does not mean every dollar withheld is returned as a lump-sum payment.
For example, someone whose benefits were withheld for several months before reaching full retirement age may receive a recalculated monthly benefit afterward. The exact amount depends on their circumstances and the applicable benefit calculation.
People who expect to earn more than the limit should report their estimated wages or self-employment income to Social Security. If their earnings change during the year, updating the estimate can help the agency make more accurate payment decisions.
The SSA provides additional details through its official retirement benefits planning resources, including information about claiming benefits, full retirement age, and the effect of work on retirement payments.
Claiming
The age at which someone begins collecting Social Security can affect the amount they receive for the rest of retirement. Eligible workers can generally begin claiming retirement benefits at age 62, but claiming before full retirement age results in a permanently reduced monthly benefit compared with waiting until full retirement age.
For people born in 1960 or later, full retirement age is 67. Claiming at 62 can reduce the retirement benefit by as much as 30% compared with the amount payable at full retirement age.
That reduction is separate from the earnings test. A person who claims early and continues working may face both a lower starting benefit and temporary withholding if their earnings exceed the applicable annual limit.
Waiting longer can increase monthly payments. Workers who delay claiming beyond full retirement age may qualify for delayed retirement credits, which generally increase benefits by 8% for each year of delay for people born in 1943 or later, up to age 70.
There is no additional delayed retirement credit for waiting beyond age 70. The financial value of claiming early or delaying depends on several factors, including health, life expectancy, current income needs, employment plans, and whether a spouse or other family member may qualify for benefits based on the worker’s record.
Someone who needs income immediately may have different priorities from a person who can continue working and cover expenses without Social Security. Comparing these options before claiming can help workers understand the long-term consequences.
Income
One common source of confusion is the difference between wages and other forms of income. The Social Security earnings test generally focuses on wages from employment and net earnings from self-employment, rather than every dollar a retiree receives.
Income that generally does not count toward the retirement earnings limit includes:
- Pension payments from previous employment.
- Annuity payments.
- Interest and dividends from investments.
- Capital gains from selling investments.
- Withdrawals from individual retirement accounts (IRAs) and other retirement accounts.
For example, a retiree who earns $20,000 in wages and receives another $15,000 in investment income would not generally count the investment income toward the earnings test. The relevant earnings figure would generally be the $20,000 in wages, assuming no other earnings apply.
By contrast, a person who earns money through self-employment may need to calculate net earnings from that work under Social Security’s rules. The timing of earnings can also matter, particularly when a person retires partway through the year.
These distinctions are important because not every income source has the same treatment under federal benefit rules. Taxable income and income counted for the Social Security earnings test are not necessarily identical.
Workers who are unsure how their earnings will affect their checks can use the SSA’s Retirement Earnings Test Calculator and review the agency’s guidance before making financial decisions.
Employment
Continuing to work after claiming Social Security has become an important consideration for many older Americans. Some retirees want to remain active, while others need employment income to cover everyday expenses that their monthly benefits do not fully meet.
Part-time employment, consulting, seasonal work, and self-employment can provide additional income. However, anyone considering these options before full retirement age should estimate annual earnings carefully.
A worker who earns slightly more than the applicable limit may face some benefit withholding, while someone whose earnings remain below the threshold generally will not have benefits withheld under the earnings test.
The timing of employment can also influence the calculation. Social Security has a special monthly earnings rule that may help some people who retire during the year and have already earned more than the annual limit. Under certain conditions, they can receive benefits for months when their earnings are sufficiently low, even if their total annual earnings exceed the standard limit.
This provision can be particularly relevant to workers who retire midway through the year after receiving substantial wages earlier in the year. Eligibility depends on the circumstances, so it is worth reviewing the SSA’s guidance rather than assuming that the annual total tells the whole story.
Costs
The decision to continue working often reflects the cost of maintaining a household in retirement. Housing, food, insurance, transportation, and health care can place pressure on a fixed income, especially for people with limited savings.
Social Security provides an important source of retirement income, but it is not designed to replace every worker’s previous earnings. The amount an individual receives depends on their earnings history, claiming age, and other applicable factors.
Annual cost-of-living adjustments can help benefits keep pace with inflation, although the effect varies across households. A general inflation adjustment may not match the price increases experienced by a particular retiree, especially if housing or medical expenses account for a large share of the budget.
For people considering work, the important question is not simply whether they can earn more than the limit. It is whether the additional wages, any temporary benefit withholding, work-related expenses, and tax consequences make the arrangement worthwhile.
A household budget can help clarify the decision. Comparing expected take-home pay with transportation costs, health insurance expenses, and any changes in benefit payments gives a more realistic picture than looking at gross wages alone.
Planning
Workers approaching retirement should review their expected income before deciding when to claim benefits or whether to continue working. The 2027 earnings limits provide a useful starting point, but individual circumstances determine how the rules affect actual payments.
Before making a decision, consider these steps:
- Estimate wages and net self-employment earnings for the year.
- Identify whether the lower or higher earnings limit applies.
- Check the expected Social Security benefit and potential withholding.
- Review how early claiming affects the monthly benefit.
- Update earnings estimates if employment or income changes.
It is also sensible to distinguish temporary withholding under the earnings test from the permanent benefit reduction associated with claiming early. These are separate rules, and understanding both can help workers avoid mistaken assumptions about their retirement income.
The 2027 limits are scheduled to rise to $25,560 for people below full retirement age throughout the year and $67,920 for those reaching full retirement age during the year, with the higher threshold applying to earnings before the month full retirement age is reached. Because benefit rules and annual thresholds can change, beneficiaries should confirm the figures and their individual circumstances directly with Social Security.
For retirees who want to keep working, the central consideration is how employment income fits into their wider retirement plan. Earning above the limit may temporarily reduce payments before full retirement age, but it does not automatically end Social Security eligibility. Knowing the earnings test, the treatment of different income sources, and the effect of claiming age can help workers make informed decisions about balancing employment and retirement benefits.