A higher Social Security cost-of-living adjustment could provide millions of retirees with additional income in 2027, but the amount left over after essential expenses may be smaller than the headline increase suggests. Rising heating costs, Medicare premiums, prescription expenses, and transportation bills could absorb part of the extra money, particularly for older Americans who rely on Social Security as their primary source of income.
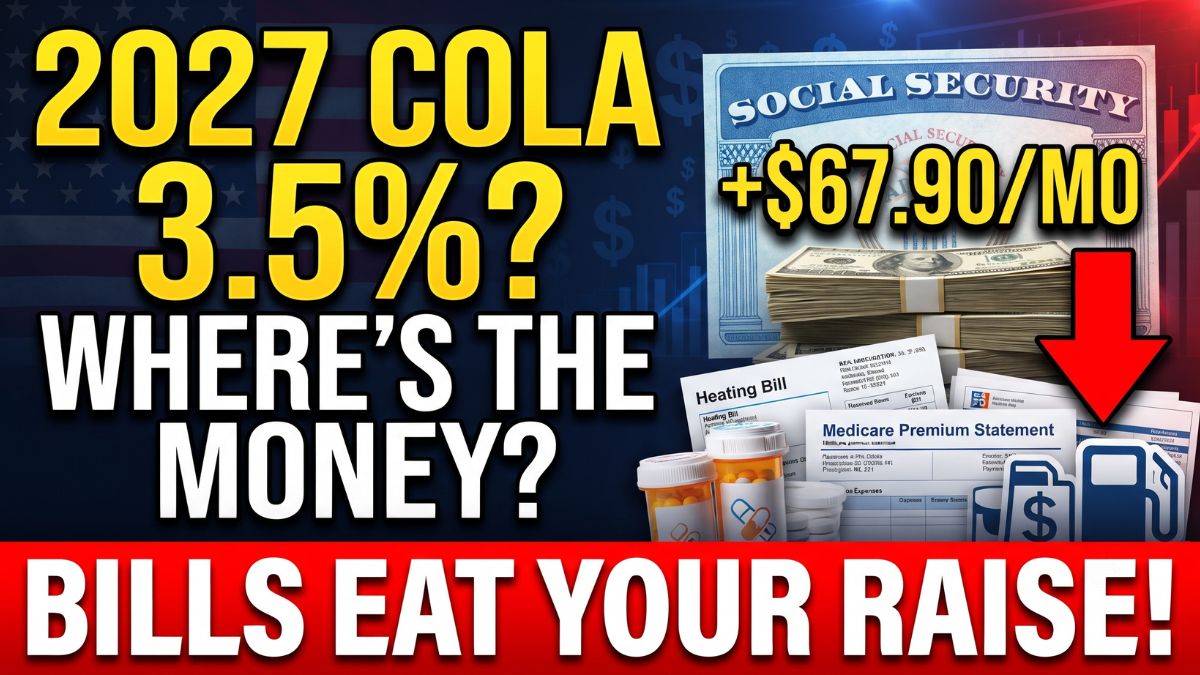
The Senior Citizens League (TSCL) has projected a 3.5% cost-of-living adjustment (COLA) for 2027, compared with the 2.8% increase for 2026. If the forecast proves accurate, a retiree receiving $2,000 per month would see a gross increase of $70. Someone receiving an average monthly benefit of $1,940.08 would gain approximately $67.90, bringing the payment to about $2,007.98.
However, the 3.5% figure is a forecast, not a confirmed adjustment. The Social Security Administration (SSA) calculates the annual increase using inflation data, and the final percentage depends on the relevant consumer price index figures. Meanwhile, retirees must contend with household expenses that do not always rise at the same rate as the overall inflation measure.
Forecast
The projected 3.5% COLA reflects expectations about inflation during the period used to calculate Social Security’s annual benefit adjustment. The SSA generally compares the average Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) for July, August, and September with the average for the same period in the previous year.
The resulting percentage change determines the annual adjustment when the index has increased. The process is intended to help Social Security benefits maintain purchasing power as consumer prices rise.
The official 2027 COLA is expected to be announced in October 2026, after the September inflation figures become available. Until the announcement, retirees should treat estimates from advocacy organizations and analysts as preliminary.
The SSA explains the calculation and publishes official updates on its Cost-of-Living Adjustments page.
The distinction matters because even a relatively small change in the final percentage can affect monthly payments across millions of beneficiaries. It also influences how retirees plan their budgets for the following year.
Payments
If the projected 3.5% adjustment becomes official, the dollar increase will depend on the amount a person currently receives. A percentage-based increase provides larger dollar gains to people with higher benefits, while those receiving smaller payments generally receive smaller increases.
The following examples illustrate what a 3.5% COLA would mean before accounting for Medicare premium changes, taxes, or other adjustments.
| Current monthly benefit | Estimated monthly increase | New monthly benefit |
|---|---|---|
| $1,500 | $52.50 | $1,552.50 |
| $1,940.08 | $67.90 | $2,007.98 |
| $2,000 | $70.00 | $2,070.00 |
| $2,500 | $87.50 | $2,587.50 |
For someone receiving $2,000 per month, an additional $70 would amount to $840 over 12 months if the full increase applied throughout the year. For a beneficiary receiving $1,500, the corresponding annual increase would be $630.
These figures show the nominal increase in income, not necessarily an improvement in purchasing power. If rent, groceries, heating, healthcare, and transportation become more expensive, some or all of the additional money may be needed to cover those bills.
The impact will vary by household. Retirees with other income sources may have more flexibility, while people who depend almost entirely on Social Security may have less room to absorb unexpected expenses.
Expenses
A COLA is designed to help benefits keep pace with inflation, but it does not guarantee that every recipient will experience the same change in living costs as the national index.
For example, a retiree who spends a large share of monthly income on heating oil and prescription medicines may face a different inflation rate from a household that spends more on services, travel, or discretionary purchases.
This difference is central to the debate over whether annual Social Security adjustments adequately reflect retirees’ expenses.
The Senior Citizens League’s 2026 survey reportedly found that about 89% of respondents considered the 2026 COLA too low. Approximately 44% said Social Security was their only source of income.
These survey findings reflect respondents’ reported experiences rather than the circumstances of every beneficiary. Nevertheless, they illustrate the financial challenges facing people with limited income flexibility.
When nearly all household income is committed to regular expenses, even a modest increase in heating or healthcare costs can require changes to grocery spending, savings withdrawals, or other purchases.
Heating
Home energy costs could be an important consideration during the 2026-2027 winter season. The National Energy Assistance Directors Association (NEADA) has been cited as projecting that heating oil expenses could be 50% higher than the previous winter.
If that estimate materializes, households that depend on heating oil could face a significant increase in seasonal costs. However, the projection should not be interpreted as a uniform increase for all older Americans.
Heating expenses depend on local weather, home insulation, energy efficiency, household size, and the type of fuel used. Retirees who heat their homes with natural gas or electricity may experience different price changes.
For someone who uses heating oil, the financial impact may also depend on when fuel is purchased and how frequently a tank needs to be refilled. A large seasonal bill can be difficult to manage when monthly income is fixed.
Eligible households may be able to obtain help through the Low Income Home Energy Assistance Program, which supports qualifying households with heating and cooling expenses.
The federal program’s eligibility information is available through the Administration for Children and Families.
Fuel
Gasoline and diesel prices can create additional pressure for retirees who drive regularly. Transportation expenses may include trips to medical appointments, grocery stores, pharmacies, and family members’ homes.
Energy markets respond to several factors, including crude oil prices, refining capacity, seasonal demand, distribution costs, and geopolitical developments. Conflict in the Middle East can affect market expectations and supply conditions, but the direction and scale of any resulting price change are uncertain.
For retirees who live in rural communities or areas with limited public transportation, driving may be difficult to avoid. Higher fuel prices can therefore affect essential activities rather than discretionary travel alone.
Fuel costs can also influence the prices of goods and services when businesses pass transportation expenses on to customers.
Still, not every retiree will experience the same effect. People who drive infrequently, use public transportation, or live close to essential services may be less exposed to fuel price increases.
A projected COLA can provide some additional flexibility, but its value will depend partly on how transportation costs change over the coming year.
Medicare
Medicare premiums are another factor that can reduce the amount of a Social Security increase available for other expenses.
Many beneficiaries have their Medicare Part B premiums deducted directly from their Social Security payments. When the standard premium increases, the amount deposited into a beneficiary’s bank account may rise by less than the gross COLA.
The figures provided for this analysis project a 2027 standard Part B premium of $209.50 per month, up from approximately $202.90. That would represent an increase of about $6.60 per month, or $79.20 over a full year.
These figures are projections and should not be treated as confirmed 2027 premiums. The official amount must be established through the relevant government announcement.
Using the estimated average Social Security increase of $67.90, subtracting a $6.60 increase in Part B premiums would leave approximately $61.30 per month before considering other changes in household costs.
Medicare Part B generally helps cover physician services, outpatient care, and certain medical equipment. However, beneficiaries can also face deductibles, coinsurance, and expenses for services that Medicare does not fully cover.
Dental, routine vision, and hearing care may create additional costs, depending on the coverage a person has.
Official information about Medicare coverage and premiums is available through Medicare.gov.
Prescriptions
Prescription coverage could further affect retirees’ budgets in 2027. Medicare Part D plans vary in their monthly premiums, covered medications, deductibles, pharmacy networks, and out-of-pocket costs.
According to the KFF figures cited for this analysis, about 4 million Part D enrollees without low-income subsidies paid no monthly premium in 2026. Some beneficiaries enrolled in zero-premium plans may face premiums in 2027 if their coverage changes.
A plan with no monthly premium in one year is not necessarily guaranteed to remain free the following year. Insurers can change premiums and other plan features, subject to applicable Medicare requirements.
Social Security analyst Mary Johnson has also reported that a prescription plan she previously used without a monthly premium is expected to cost more than $19 per month in 2027. That example illustrates the potential impact of a plan change, but it does not mean all beneficiaries will face the same increase.
For someone who experiences both the projected $6.60 Part B premium increase and a new Part D premium exceeding $19, more than $25 of the estimated $67.90 monthly COLA increase could be absorbed by those two expenses alone.
That calculation excludes heating, fuel, copayments, deductibles, and other medical expenses. It also relies on projections that have not all been finalized.
Beneficiaries can compare available Part D plans during Medicare’s annual enrollment period, paying attention to the medications they use, pharmacy access, monthly premiums, and total expected costs.
Budgeting
Retirees can prepare for the next benefit year by reviewing their household budgets before the official COLA is announced. Listing essential expenses separately can help identify which costs are most likely to affect available income.
Heating, transportation, insurance, food, and prescription medicines deserve particular attention when those categories represent a large portion of monthly spending.
It may also be useful to review Medicare coverage rather than automatically renewing an existing plan. A plan with a low monthly premium may not offer the lowest overall cost for a person who takes several prescription medicines or requires frequent medical care.
People with limited incomes can also investigate whether they qualify for assistance with energy bills, prescription costs, or Medicare expenses. Eligibility requirements vary by program, income, household circumstances, and location.
The projected 3.5% Social Security COLA could provide additional income in 2027, but its practical value will depend on the final adjustment and the costs individual households face. Higher heating bills, fuel prices, Medicare premiums, and prescription expenses could reduce the amount left for other needs.
Until the SSA confirms the COLA and the relevant 2027 premiums become official, retirees should use current figures as planning estimates rather than guaranteed outcomes. A careful review of income, essential bills, and available assistance can help households prepare for the year ahead without assuming that the full benefit increase will translate into additional spending money.