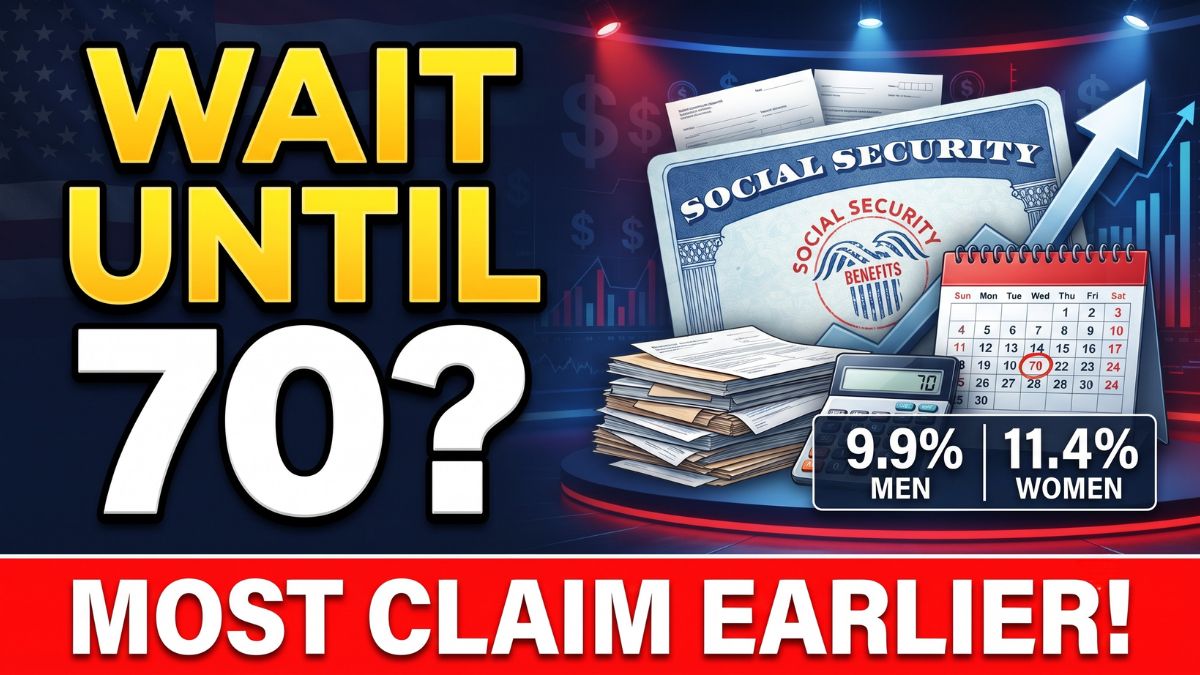
Choosing when to claim Social Security is one of the most important decisions Americans face as they approach retirement. Starting benefits early provides income sooner, while waiting can increase the monthly payment for the rest of a retiree’s life. For people who can afford to delay, claiming at age 70 offers the highest standard retirement benefit available through delayed retirement credits.
Recent claiming data show that more retirees are choosing to wait. In 2024, approximately 9.9% of men and 11.4% of women claimed Social Security at age 70 or later. These figures represent a substantial increase from earlier years, although most retirees still begin receiving benefits before reaching 70.
The decision is not simply about maximizing a monthly check. Health, household income, savings, employment, marital status, and taxes can all influence the best time to claim. Knowing how the program works and what the latest figures reveal can help future retirees evaluate their options.
Benefits
Social Security retirement benefits are available as early as age 62 for eligible workers. However, claiming before full retirement age generally reduces the monthly payment permanently. Waiting beyond full retirement age can increase the benefit through delayed retirement credits.
Full retirement age, commonly called FRA, depends on a person’s birth year. For individuals born in 1960 or later, it is 67. Someone born before 1960 may have a lower full retirement age, depending on their birth year.
For retirees whose full retirement age is 67, delaying benefits until 70 can increase the monthly payment by approximately 24% compared with claiming at 67, assuming the standard delayed retirement credit rules apply. The increase results from three years of delayed retirement credits, which generally add 8% annually.
The Social Security Administration explains these rules in its official retirement planning guidance: Delayed Retirement Credits.
The increase is particularly relevant for people who expect to depend on Social Security for a substantial portion of their retirement income. A higher monthly benefit can provide additional income throughout retirement and may reduce the need to draw as heavily on savings later in life.
However, delayed retirement credits stop accumulating at age 70. Waiting beyond that point does not increase retirement benefits through additional delayed credits, although other factors, such as additional earnings, may affect a person’s benefit calculation.
Trends
The share of retirees waiting until age 70 to claim Social Security has increased considerably over the past two decades. According to the figures provided for this analysis, only about 1% of men waited until age 70 or later in 2011. By 2024, the proportion had reached approximately 9.9%.
The change indicates that delayed claiming has become more common, although it remains less popular than claiming at earlier ages.
Several factors may contribute to this pattern. Greater awareness of delayed retirement credits, changes in retirement planning practices, and concerns about maintaining income throughout a potentially long retirement may influence claiming decisions.
Changes to Social Security claiming rules may also have affected how some households approach retirement. Legislation enacted in 2015 phased out certain strategies that had allowed eligible married couples to coordinate their applications to increase combined benefits.
Nevertheless, the available figures do not establish a single explanation for the increase. Retirees have different financial resources, employment histories, and family circumstances, all of which can affect the age at which they apply.
The broader trend is clear: claiming at 62 has become less common among men in the cited data, while waiting until later ages has become more prevalent.
Men
In 2024, approximately 9.9% of men claimed Social Security retirement benefits at age 70 or later. That compares with about 1% in 2011, representing a notable change in claiming behavior.
The share of men claiming at age 62 has also declined. In 2001, approximately 55% of men in the cited data claimed benefits at the earliest eligible age. By 2024, that figure had fallen to 25%.
Despite this shift, age 70 remained a less common claiming age than several earlier ages. Ages 62 and 66 were among the most frequently reported claiming ages for men in 2024.
These figures highlight an important distinction between choosing to maximize monthly benefits and choosing to receive benefits sooner. A retiree who claims at 62 may receive payments for several additional years compared with someone who waits until 70. However, the earlier claimant generally receives a smaller monthly amount.
The financial outcome depends partly on how long each person lives, how much they would receive at different claiming ages, and whether they have enough income to cover expenses while delaying.
Men who continue working may also have more flexibility to postpone claiming, particularly if their earnings can cover living expenses. Others may need Social Security income sooner because of limited savings, health concerns, or changes in employment.
Women
Women were somewhat more likely than men to wait until age 70 or later in 2024. Approximately 11.4% of women claimed benefits at age 70 or later, compared with 9.9% of men.
The difference was 1.5 percentage points. The figures also indicate that women were more likely than men to delay claiming in each year from 2001 through 2024.
As with men, the proportion of women waiting until age 70 has increased over time, while claiming at the earliest eligible age has become less common.
Several considerations could help explain why delaying may be relevant to some women, although the data do not establish the reasons behind the difference.
Women have a longer average life expectancy than men in the United States. As a result, some women may receive Social Security benefits over a longer period, making the size of the monthly payment an important retirement planning consideration.
Marital status can also influence claiming decisions. A woman who is married to a higher-earning spouse may need to consider how the timing of that spouse’s claim could affect potential survivor benefits. Divorced individuals and widows may face different considerations depending on their eligibility and circumstances.
However, women do not necessarily benefit more from delaying in every situation. A shorter work history, lower lifetime earnings, limited savings, or immediate financial needs may make an earlier claim more practical.
The appropriate claiming age depends on the individual’s circumstances, not gender alone.
Comparison
The figures below summarize the main trends described in the available data.
| Claiming measure | Men | Women |
|---|---|---|
| Claimed at age 70 or later in 2024 | 9.9% | 11.4% |
| Claimed at age 62 in 2001 | 55% | Not specified |
| Claimed at age 62 in 2024 | 25% | Not specified |
| Overall pattern from 2001 to 2024 | More delayed claims | More delayed claims |
The comparison shows that waiting until 70 has become more common among both men and women. Women had a higher share of delayed claims in 2024, but the difference was relatively small.
These figures should not be interpreted as evidence that delaying is the right decision for every retiree. They describe when people claimed benefits, not whether those individuals received more in total lifetime benefits by waiting.
The data also do not show how individual claiming decisions were affected by income, health, marital status, or access to retirement savings.
Timing
The choice between claiming early and waiting until 70 often involves balancing immediate income against a larger future payment.
Consider a hypothetical retiree whose full retirement age is 67. If the person qualifies for a $2,000 monthly benefit at that age, waiting until 70 could raise the amount to approximately $2,480 before considering cost-of-living adjustments or other changes.
That additional $480 per month could make a meaningful difference over a long retirement. However, the retiree would have forgone three years of payments while waiting.
This creates a break-even calculation. The retiree needs to determine how long it would take for the larger payments received after age 70 to offset the benefits that were not collected between ages 67 and 70.
The exact break-even age depends on the benefit amounts, applicable adjustments, taxes, and other individual circumstances. A retiree who lives substantially beyond the break-even point may receive more in cumulative benefits by delaying. Someone who dies earlier may collect less in total retirement benefits than if they had claimed sooner.
This calculation is useful, but it does not capture every consideration. A larger monthly payment later in life can provide protection against longevity risk, meaning the possibility of living longer than expected and exhausting other financial resources.
Conversely, a retiree with limited savings may find it difficult to wait several years without Social Security income.
Finances
A person’s financial position is central to deciding when to claim benefits. Delaying can be more manageable for someone with a pension, investment income, employment earnings, or sufficient savings to cover expenses.
People who lack these resources may need to claim earlier to pay for housing, food, healthcare, and other essential costs.
Continuing to work can also affect the decision. Before full retirement age, Social Security applies an earnings test that may temporarily withhold some benefits when earnings exceed the applicable annual limit. Different rules apply during the year a person reaches full retirement age, and the earnings test no longer applies after reaching that age.
Official details are available through the Social Security Administration’s Retirement Earnings Test guidance.
Taxes are another consideration. Depending on a person’s combined income, a portion of Social Security benefits may be subject to federal income tax. Delaying benefits could create an opportunity to draw down traditional retirement accounts during the years before Social Security begins, but withdrawals can also increase taxable income.
Some retirees use this period to consider Roth conversions. These transactions can have long-term tax implications, so the potential benefits should be evaluated alongside current tax brackets, future required minimum distributions, and other sources of income.
A decision to delay should therefore consider the entire retirement plan rather than focusing solely on the monthly Social Security payment.
Marriage
Married couples may need to evaluate Social Security claiming decisions together rather than treating each spouse’s benefits as a separate issue.
When one spouse has substantially higher lifetime earnings, delaying that person’s retirement benefit may increase the potential survivor benefit available to the other spouse. The precise amount depends on Social Security rules and the couple’s individual circumstances.
This can be particularly important when one spouse expects to rely on the other’s income record for financial security after a death.
However, couples should not assume that every delayed claim automatically produces the same survivor benefit outcome. Eligibility, claiming history, benefit amounts, and other program rules all matter.
Divorced individuals may also qualify for certain benefits based on a former spouse’s record if they meet the applicable requirements. These situations can affect the best claiming strategy, making individualized estimates important.
Couples can compare benefit estimates through the Social Security Administration’s official Retirement Benefits resources.
Planning
Before deciding when to claim Social Security, retirees should compare estimates at several ages, such as 62, full retirement age, and 70. The Social Security Administration’s online tools and personal accounts can help individuals review their estimated benefits based on their earnings records.
It is also useful to prepare a realistic retirement budget. Housing costs, healthcare expenses, debt payments, and regular household spending should be considered alongside savings, pensions, and investment income.
People approaching retirement should review their health and family history without assuming that life expectancy can be predicted precisely. They should also consider whether a larger guaranteed monthly benefit would be valuable if they live well into their 80s or 90s.
For married households, reviewing both spouses’ estimates can help clarify how different claiming dates might affect combined retirement income and potential survivor benefits.
The growing share of people waiting until age 70 shows that delayed claiming has become a more visible part of retirement planning. Yet the figures also show that most retirees do not wait that long. The right decision depends on whether a person can afford to delay, how long they expect to need retirement income, and how Social Security fits into their broader financial plan. For some, waiting can provide a higher monthly payment and greater protection later in life. For others, claiming earlier may be the more practical choice.