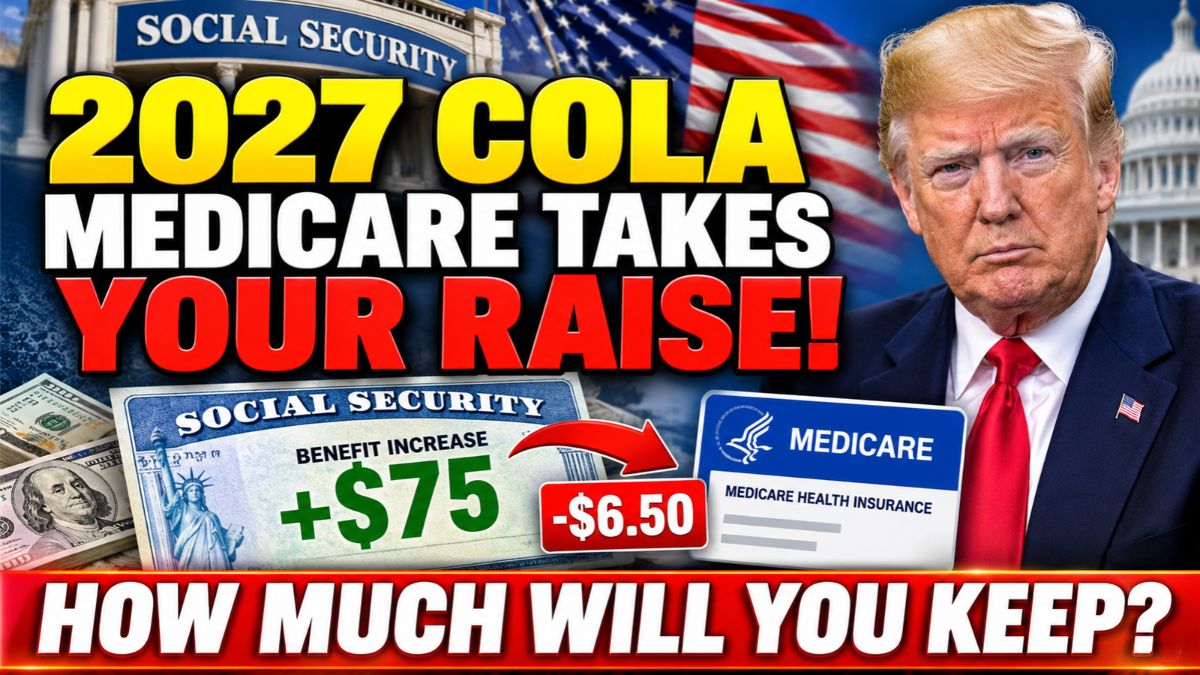
Millions of American retirees are expecting higher Social Security payments in January 2027 following a projected 3.6% cost-of-living adjustment (COLA). The increase is intended to help older Americans manage rising expenses, including groceries, housing, healthcare, and other essential costs. However, the full increase may not translate into additional money in retirees’ bank accounts.
The reason is the scheduled increase in Medicare Part B premiums. The standard monthly premium is expected to rise by $6.50 in 2027, reducing the amount of the Social Security increase available to retirees who have their Medicare premiums deducted directly from their benefits.
For an average retired worker, the estimated $75 monthly Social Security increase would effectively fall to approximately $68.50 after accounting for the higher Part B premium. Although this is still an increase, the impact will vary depending on the size of an individual’s existing Social Security payment.
Retirees receiving smaller monthly benefits could see a larger portion of their COLA absorbed by the Medicare premium adjustment. Understanding how these two changes work together can help beneficiaries estimate how much additional income they may actually receive in 2027.
Increase
The projected 2027 Social Security COLA is 3.6%, which would increase the average monthly retirement benefit from approximately $2,095 to $2,170.
The adjustment is calculated using inflation data and is intended to help Social Security beneficiaries maintain their purchasing power as consumer prices change.
However, the increase in Social Security payments does not automatically mean retirees will have the same amount of additional disposable income.
According to the Social Security Administration’s 2027 COLA information, the average retired worker benefit is expected to increase by approximately $75 per month under the figures discussed here.
At the same time, the standard Medicare Part B premium is scheduled to increase from $202.90 to $209.40 per month, adding $6.50 to the monthly healthcare expense.
For beneficiaries who pay this premium through automatic deductions from Social Security, the higher cost will reduce the net benefit increase.
Premium
Medicare Part B generally covers medically necessary services, outpatient care, physician visits, preventive services, and certain medical equipment.
Most Medicare beneficiaries pay a standard monthly premium for this coverage. The amount is adjusted periodically, and changes can affect retirees who rely heavily on Social Security income.
In 2027, the standard monthly Part B premium is expected to reach $209.40 under the figures provided.
For someone receiving the average retirement benefit, the calculation would look like this:
| Description | Monthly Amount |
|---|---|
| Previous average Social Security benefit | $2,095 |
| Estimated 3.6% COLA increase | $75 |
| New average monthly benefit | $2,170 |
| Standard Part B premium | $209.40 |
| Remaining amount after Part B deduction | $1,960.60 |
This calculation assumes the beneficiary pays only the standard Part B premium and has no additional deductions. Actual take-home payments may differ because of taxes, Medicare Advantage premiums, prescription drug coverage, or other adjustments.
Impact
The $6.50 Medicare premium increase will not affect every retiree in the same way. Its impact depends largely on the amount of Social Security benefits someone currently receives.
A person with a smaller monthly benefit generally receives a smaller dollar increase from the 3.6% COLA. However, the standard Part B premium increase remains the same for most beneficiaries paying the standard rate.
As a result, lower-income retirees may lose a larger percentage of their annual COLA increase to the higher Medicare premium.
The following table illustrates how the adjustment could affect different benefit levels.
Social Security increase before and after the Medicare Part B premium increase
| Current Monthly Benefit | 3.6% Monthly COLA | Increase After $6.50 Premium Hike | COLA Absorbed |
|---|---|---|---|
| $1,000 | $36 | $29.50 | 18% |
| $1,500 | $54 | $47.50 | 12% |
| $2,095 | $75 | $68.50 | 9% |
| $2,500 | $90 | $83.50 | 7% |
| $3,000 | $108 | $101.50 | 6% |
Source: Calculations based on the supplied 3.6% COLA estimate and a $6.50 monthly Part B premium increase. Percentages are rounded.
These figures demonstrate why the same Medicare premium increase can have different financial consequences for retirees.
Retirees
The impact is particularly relevant for people receiving smaller Social Security payments.
According to the federal data referenced in the supplied information, more than 5.7 million retired workers received less than $1,000 per month in Social Security benefits in June 2026.
For someone receiving $1,000 monthly, a 3.6% COLA would add approximately $36 to the benefit. After accounting for the $6.50 increase in Medicare Part B premiums, the remaining monthly gain would be $29.50.
This means the premium increase would absorb approximately 18% of the additional income generated by the COLA.
By comparison, someone receiving $3,000 monthly would receive an estimated $108 increase. After the same premium adjustment, approximately $101.50 would remain.
The difference highlights how healthcare expenses can affect retirees differently depending on their existing income.
Protection
Some retirees may be protected by a federal provision known as the Medicare hold harmless rule.
This rule generally prevents an increase in Medicare Part B premiums from reducing a beneficiary’s Social Security payment below its previous amount, provided certain eligibility conditions are met.
The protection is particularly relevant when Medicare premium increases exceed the annual Social Security COLA or when the COLA is relatively small.
However, the rule does not apply to everyone. Certain beneficiaries, including some new Medicare enrollees and people subject to income-related premium adjustments, may not qualify.
Retirees can review the Social Security Administration’s explanation of the hold harmless provision to understand how the protection works.
Surcharges
Another consideration is the income-related monthly adjustment amount, commonly known as IRMAA.
Some Medicare beneficiaries pay more than the standard Part B premium because their income exceeds specific thresholds. These additional charges are generally based on income reported on an earlier federal tax return.
According to the Centers for Medicare and Medicaid Services, the income thresholds and premium details for 2027 provide additional information about these adjustments.
For retirees with higher incomes, IRMAA can increase monthly Medicare expenses beyond the standard premium.
This means their actual Social Security payment after Medicare deductions may be lower than the estimates shown in the table.
Planning
The 2027 Social Security increase could provide additional financial support for retirees, but Medicare premium changes will reduce part of that benefit for people paying Part B through Social Security deductions.
Retirees should review their benefit statements, Medicare premium notices, and monthly expenses to understand the difference between their gross benefit and the amount deposited into their accounts.
Those receiving smaller Social Security payments may need to pay particular attention because a fixed premium increase represents a larger share of their COLA.
Ultimately, the projected 3.6% adjustment would still increase Social Security benefits, but the amount retirees actually keep will depend on Medicare premiums and other deductions. Knowing these changes together can help older Americans prepare their household budgets and make more informed decisions about retirement expenses.