Millions of Americans approach retirement with plans to combine Social Security benefits and income from work. For some, a part-time job provides extra spending money. For others, continuing to work is necessary to cover housing, groceries, insurance, and healthcare costs. But if you claim Social Security before reaching full retirement age, your earnings could affect how much you receive in benefits during the year.
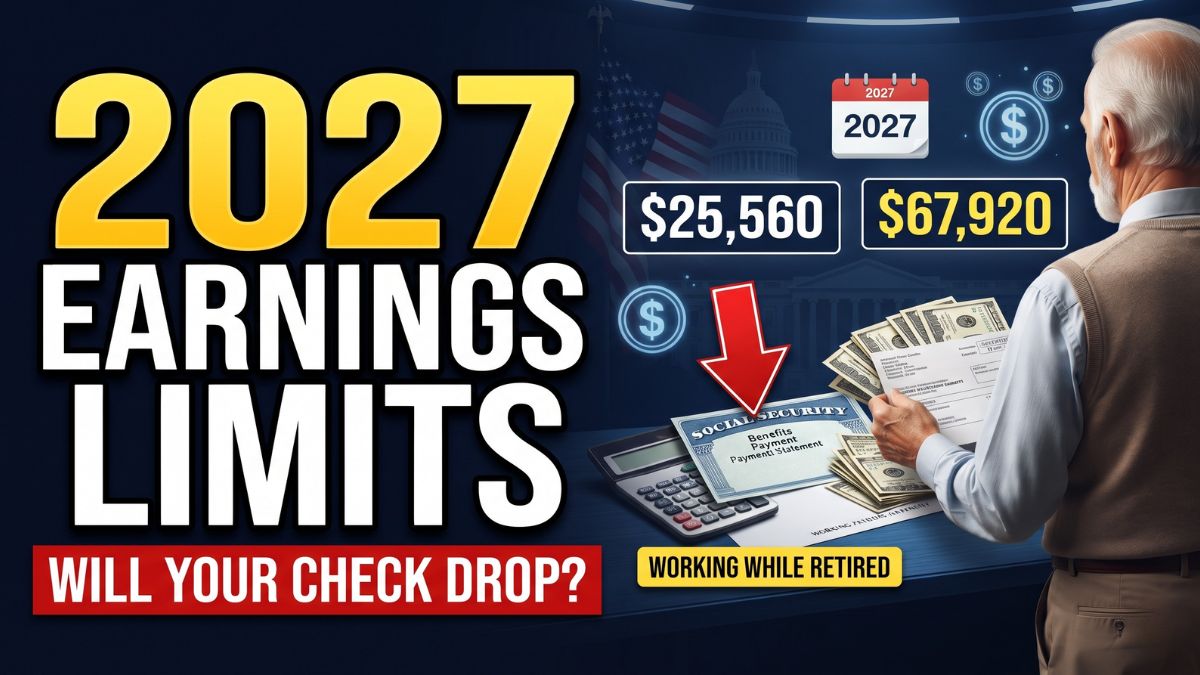
The 2027 earnings limit is an important figure for retirees who plan to keep working. The reported threshold of $25,560 would determine when the Social Security Administration (SSA) begins withholding some benefits from eligible recipients who have not yet reached full retirement age. However, the earnings test does not apply to everyone, and benefits withheld under this rule are not necessarily lost permanently.
Knowing the rules can help retirees decide when to claim benefits, how much to work, and what to expect from their monthly payments. It is also important to distinguish between the earnings limit and other retirement rules, including early claiming reductions, delayed retirement credits, and taxes on Social Security income.
Basics
Social Security retirement benefits can generally begin at age 62, provided the individual meets the program’s eligibility requirements. Claiming early, however, usually means accepting a lower monthly payment than if benefits began at full retirement age.
For people born in 1960 or later, full retirement age is 67. Someone who claims at 62 may receive a retirement benefit that is up to 30% lower than the amount available at full retirement age, depending on their circumstances and claiming history.
Waiting can increase the monthly benefit. Eligible retirees who delay claiming beyond full retirement age generally earn delayed retirement credits until age 70. For people born in 1943 or later, these credits typically increase retirement benefits by 8% for each full year of delay after full retirement age.
The decision to claim early or wait depends on several factors, including current income, savings, health, expected retirement expenses, and whether a spouse or other family member may qualify for benefits based on the worker’s record.
The SSA provides an official explanation of retirement eligibility and claiming ages through its Retirement Benefits guide. Reviewing this information can help workers compare their options before making a decision.
Limits
The Social Security earnings test applies to people receiving retirement benefits who have not yet reached full retirement age. When their earnings from work exceed the applicable annual threshold, the SSA may withhold a portion of their benefits.
Under the reported 2027 figures, the annual limit for people below full retirement age throughout the year would increase to $25,560, compared with $24,480 in 2026. The official 2027 threshold should be confirmed through the SSA’s annual updates before retirees rely on it for financial planning.
Under the standard earnings test, the SSA withholds $1 in benefits for every $2 earned above the applicable limit.
For example, suppose the applicable annual limit is $25,560 and a retiree earns $30,560 in wages during the year. The amount above the threshold would be $5,000. Under the standard rule, the SSA could withhold $2,500 in benefits.
This calculation does not mean the SSA automatically reduces every monthly payment by a fixed percentage. The agency determines the amount to withhold based on the recipient’s benefit entitlement and earnings information. Depending on the circumstances, withholding may affect one or more payments until the required amount has been accounted for.
The earnings limit also does not mean retirees must stop working once their wages reach the threshold. They can continue earning income, but their Social Security payments may be withheld under the applicable rules.
Exceptions
A different earnings limit applies during the calendar year a person reaches full retirement age. Under the reported 2027 figures, the limit for that year would be $67,920. Only earnings received before the month the individual reaches full retirement age count toward this higher threshold.
The standard earnings test ends when a person reaches full retirement age. From that point forward, there is no annual earnings limit for Social Security retirement benefits. A beneficiary can continue working full-time, earn a substantial salary, or operate a business without having retirement benefits withheld under the earnings test.
This distinction matters for people approaching age 67 who intend to continue working. The rules that apply before full retirement age can be substantially different from those that apply afterward.
For example, someone who reaches full retirement age in September would generally have earnings counted under the higher annual limit only if they were received before September. Earnings from September onward would not be subject to the retirement earnings test.
The SSA also has a special monthly rule that may help certain people who retire partway through a year after earning more than the annual limit. In qualifying circumstances, a person can receive benefits for a month in which earnings are below the applicable monthly threshold, even if their total earnings for the year exceeded the annual limit.
Retirees considering this option should review the SSA’s official guidance on working while receiving retirement benefits. The guidance explains the annual test, the special monthly rule, and the treatment of earnings around full retirement age.
Recovery
One common misunderstanding is that Social Security benefits withheld because of employment earnings disappear permanently. In many cases, the SSA recalculates the benefit at full retirement age to account for months in which payments were withheld under the earnings test.
The adjustment reflects the months for which benefits were withheld. It can increase the beneficiary’s monthly payment going forward, helping account for the period when payments were not received.
However, this process is not the same as receiving a refund of every dollar withheld. A retiree should not expect an automatic lump-sum payment equal to the amount withheld during earlier working years.
The distinction is important when deciding whether to keep working while receiving benefits. Withholding can create a temporary reduction in cash flow, even if the person’s benefit is later adjusted. Anyone relying on Social Security to pay monthly bills should account for that possibility when preparing a budget.
The earnings test is also separate from the permanent reduction that generally results from claiming retirement benefits before full retirement age. Reaching full retirement age does not ordinarily erase the early-claiming reduction itself. Instead, the SSA’s adjustment for withheld months accounts for the earnings test.
Retirees should therefore consider two separate questions: whether claiming early reduces their initial benefit and whether their earnings will trigger withholding after they begin collecting payments.
Income
The earnings test does not count every source of income. It generally applies to wages from employment and net earnings from self-employment, rather than a person’s entire annual income.
Common income sources excluded from the earnings test include:
- Pension payments from previous employment
- Annuity payments
- Interest and dividends
- Capital gains
- Withdrawals from individual retirement accounts and other retirement accounts
Consider a retiree who receives $20,000 in wages and $15,000 in investment income during a year. For the earnings test, the $20,000 in wages would generally count, while the investment income would not be added to the calculation.
The treatment of self-employment income can require closer attention. Business owners may need to consider net earnings and the timing of their work when determining how the earnings test applies. A professional who retires midway through a year, for instance, may need to distinguish income earned from work performed before retirement from other payments received afterward.
It is also important to separate the earnings test from federal income taxes. Investment income, retirement account withdrawals, and other sources of income that are excluded from the earnings limit may still affect whether a portion of Social Security benefits is taxable.
The earnings test determines whether some retirement benefits must be withheld because of work. Tax rules determine whether benefits and other income create a federal income tax liability. These are separate calculations, and retirees may need to plan for both.
Pressures
Financial needs are one reason some Americans continue working after claiming Social Security. Monthly benefits provide a foundation for retirement income, but they may not cover every household’s living costs.
Housing, food, transportation, insurance, and healthcare can take up a large share of a retiree’s budget. People who enter retirement with limited savings may need employment income to bridge the gap between their Social Security payments and their expenses.
Longer life expectancies also affect retirement planning. Savings accumulated during a working career may need to support a household for decades. People who retire early may have to spread their resources across a longer period, making budgeting and withdrawal decisions particularly important.
Cost-of-living adjustments can help benefits keep pace with inflation, but they do not necessarily match every retiree’s personal expenses. Someone facing higher rent, rising insurance premiums, or significant medical bills may experience a different rate of inflation from the overall measure used to calculate annual benefit adjustments.
Any reported 2027 cost-of-living adjustment should be checked against an official SSA announcement rather than assumed from preliminary reports. The adjustment changes monthly benefit amounts, while the earnings test determines whether benefits are withheld because of work. These two policies affect retirement income in different ways.
For broader information about annual benefit changes, retirees can consult the SSA’s official cost-of-living adjustment information.
Planning
Retirees who expect to work in 2027 can take several practical steps to prepare for the earnings test. The first is to estimate annual wages and compare them with the limit that applies to their age and circumstances.
Those who expect to earn more than the threshold should consider how potential withholding might affect their monthly budget. It may be useful to maintain cash reserves for essential expenses rather than assume the full Social Security payment will arrive every month.
The timing of retirement also matters. Someone who stops working partway through the year may have a different earnings pattern from someone who works throughout the year. The SSA’s rules, including its special monthly test in qualifying situations, can affect how benefits are paid.
Before making a claiming decision, workers should compare the potential benefits of claiming early with the advantages of waiting. An early claim provides income sooner, while delaying can increase the monthly benefit for eligible individuals. Neither option is automatically best for everyone.
It is also worth reviewing household income as a whole. Employment wages, Social Security, pensions, investment income, and retirement account withdrawals may all contribute to financial security, even though they are treated differently under the earnings test.
The most reliable approach is to confirm the applicable 2027 limits directly with the SSA, review personal benefit estimates, and account for both potential withholding and tax obligations. Because annual thresholds can change, retirees should avoid basing long-term decisions solely on an unconfirmed figure.
Working while receiving Social Security does not automatically eliminate retirement benefits. The effect depends primarily on age, earnings from work, and the rules applicable to the individual. By knowing these distinctions, retirees can make more informed choices about employment, claiming dates, and monthly expenses.