Retirement planning often revolves around one important question: When can you stop working and receive your full Social Security retirement benefit? For Americans approaching retirement, the answer depends partly on their birth year. Although people can generally claim retirement benefits as early as age 62, doing so before reaching full retirement age can permanently reduce their monthly payments.
The Social Security retirement age has gradually increased under legislation enacted decades ago. As a result, workers born in different years face different eligibility milestones, even if they retire only a few months apart. These changes can influence when people choose to claim benefits, how much they receive each month, and whether continuing to work makes financial sense.
In 2026, knowing the distinction between age 62, full retirement age, and age 70 remains important for anyone preparing to claim Social Security. Another consideration is the annual cost-of-living adjustment, which can change benefit payments but does not replace the rules governing retirement age.
Here is what retirees and workers nearing retirement should know about the birth-year schedule, early claiming reductions, delayed retirement credits, and upcoming benefit adjustments.
Changes
The full retirement age, commonly called FRA, is the age at which a person becomes eligible for their full Social Security retirement benefit based on their earnings record. It is not necessarily the age when someone must stop working, nor is it the earliest age at which benefits can begin.
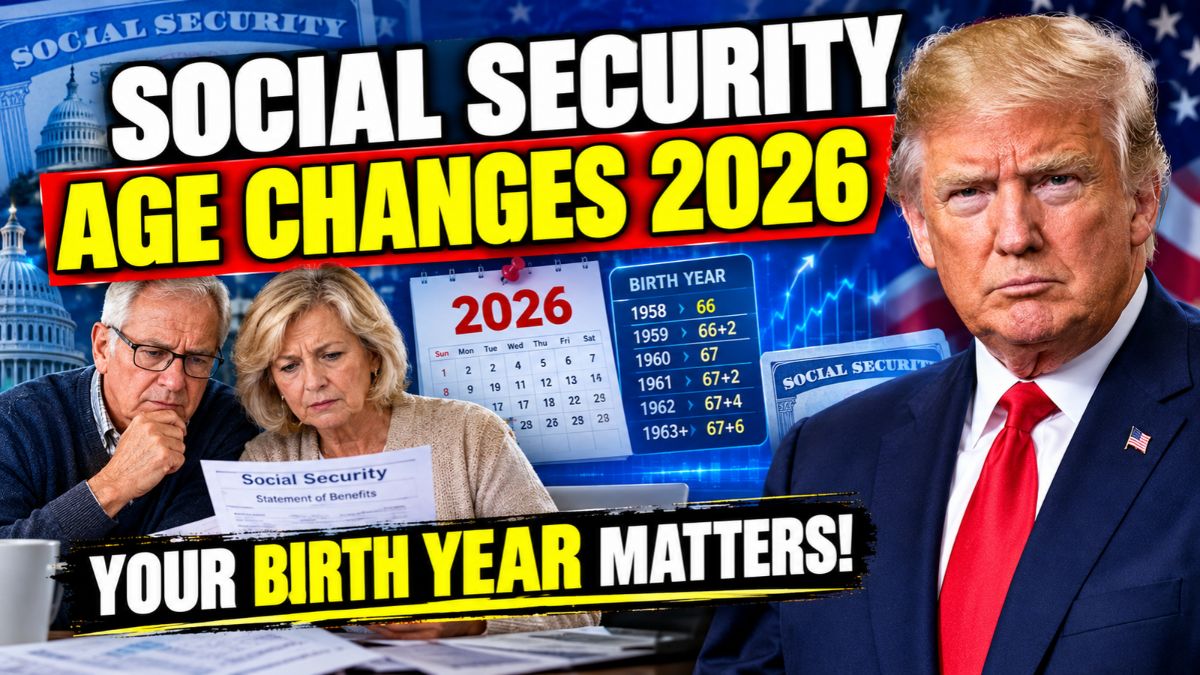
For people born between 1943 and 1954, full retirement age is 66. The schedule then increases gradually for later birth years. People born in 1955 have a full retirement age of 66 years and two months, while those born in 1956 have an FRA of 66 years and four months.
The schedule continues in two-month increments until it reaches age 67 for people born in 1960 or later.
These changes stem from amendments to Social Security legislation enacted in 1983. The legislation gradually raised the full retirement age to reflect long-term program considerations and spread the transition across multiple birth cohorts.
The official background is available in the Social Security Administration’s history of the 1983 amendments.
Schedule
Your birth year determines the full retirement age that applies to you. The following table summarizes the standard schedule for people born in 1943 or later.
| Birth year | Full retirement age |
|---|---|
| 1943-1954 | 66 years |
| 1955 | 66 years, 2 months |
| 1956 | 66 years, 4 months |
| 1957 | 66 years, 6 months |
| 1958 | 66 years, 8 months |
| 1959 | 66 years, 10 months |
| 1960 or later | 67 years |
For someone born in 1959, for example, full retirement age is 66 years and 10 months. A person born in 1960 or later must reach age 67 to qualify for their full retirement benefit under the standard schedule.
This distinction is particularly relevant to people who are comparing retirement dates with a spouse, sibling, or former colleague. Two people who appear to be close in age may face slightly different claiming rules because their birth years fall into different categories.
The gradual increase also means that the phrase “retirement age” can be misleading. There is no single age at which every American must retire or begin receiving Social Security. The relevant age depends on the benefit rules and the individual’s circumstances.
Claiming
Eligible workers can generally begin receiving Social Security retirement benefits at age 62. However, claiming before full retirement age means accepting a reduction in the monthly amount, generally for as long as the person receives retirement benefits.
The reduction depends on how early someone claims. Under the standard rules, people whose full retirement age is 67 can receive approximately 70% of their full retirement benefit if they start at age 62. That represents a 30% reduction compared with claiming at full retirement age.
For example, consider a worker whose estimated monthly benefit at full retirement age is $1,000. If the worker was born in 1960 or later and claims at age 62, the monthly payment could be approximately $700.
The difference becomes more significant over time. A $300 monthly reduction amounts to $3,600 over 12 months, before accounting for future cost-of-living adjustments. For someone who depends heavily on Social Security, that difference can affect the ability to cover routine expenses throughout retirement.
However, claiming early is not necessarily the wrong decision for everyone. Some people need income because they have stopped working, have limited savings, or face health concerns. Others may prefer to begin receiving benefits earlier rather than wait for a larger monthly payment.
The key is to understand the financial trade-off before submitting a claim. The SSA explains how early claiming affects benefits in its official retirement age reduction guide.
Delaying
Waiting beyond age 62 can help protect the value of a person’s monthly retirement benefit. For many workers, reaching full retirement age means qualifying for the full benefit calculated from their earnings record, without the reduction associated with early claiming.
There may also be an advantage to waiting beyond full retirement age. Eligible retirees generally earn delayed retirement credits for each month they postpone claiming, up to age 70.
For people born in 1943 or later, these credits typically increase benefits by 8% for each full year of delay after full retirement age. Someone with a full retirement age of 67 could therefore receive a benefit approximately 24% higher by waiting until age 70, compared with claiming at 67, assuming the applicable rules and eligibility requirements are met.
Using a simplified example, a person eligible for $1,000 per month at age 67 could receive approximately $1,240 per month at age 70 before considering cost-of-living adjustments or other factors.
The increase can provide a higher monthly income for the rest of retirement. However, delaying also means giving up payments that could have been collected during the waiting period.
People deciding whether to delay should consider their health, expected longevity, household expenses, other sources of income, and eligibility for benefits through a spouse. The decision is not simply about obtaining the largest possible monthly payment. It is about choosing a claiming strategy that fits the person’s financial circumstances.
One important limitation is that delayed retirement credits stop at age 70. Waiting beyond that point does not increase retirement benefits through additional delayed credits, so eligible workers generally have little reason to postpone claiming solely to earn a larger benefit after age 70.
Timeline
Although retirement-age changes remain important in 2026, the gradual increase in the full retirement age has already reached its scheduled endpoint for people born in 1960 or later.
This distinction matters because some reports describe the retirement age as changing in a particular year when the schedule actually depends on birth year. The final transition to a full retirement age of 67 applies to people born in 1960. It does not mean that every American’s retirement age increases again during 2026.
A person reaching age 66 in 2026, for instance, may already have passed full retirement age if they were born in 1960, depending on their exact birth date and the relevant benefit rules. Another person who turns 62 in 2026 may still have several years to wait before reaching full retirement age.
Workers should therefore avoid relying solely on their age during the current calendar year. Their birth year, month of birth, and planned claiming date can all affect their benefit calculation.
The SSA offers tools and guidance through its Plan for Retirement resource. Workers can use the agency’s resources to review their estimated benefits, understand the claiming schedule, and compare different retirement dates.
COLA
The cost-of-living adjustment, or COLA, is another important factor for people receiving Social Security. Unlike the full retirement age, which determines when a person qualifies for an unreduced retirement benefit, the COLA adjusts benefit amounts to help account for changes in consumer prices.
The SSA generally announces the annual adjustment in the fall, with the updated benefit amounts taking effect in December and appearing in payments beginning in January of the following year.
For 2027, estimates circulated before the official announcement may provide an indication of a potential increase, but projections should not be treated as confirmed benefit amounts. The final adjustment depends on the applicable inflation measure and the official calculation.
A projected increase of 3.6%, for example, would mean that a $1,500 monthly benefit increased by approximately $54, bringing it to $1,554 before any other applicable deductions or adjustments. That example is illustrative, not confirmation of the 2027 COLA.
The actual impact on a household depends on its current benefit amount and expenses. Housing, food, utilities, insurance, and healthcare costs may change at different rates, so an annual increase does not necessarily cover every additional expense.
Retirees should also remember that a COLA does not reverse a reduction caused by claiming early. If someone receives a permanently reduced retirement benefit because they claimed before full retirement age, annual adjustments generally apply to the benefit they are entitled to receive.
For confirmed annual adjustments and related announcements, the SSA’s official COLA information page is the most reliable source.
Planning
Before choosing when to claim Social Security, workers should review their estimated benefits at several different ages. Comparing the amounts available at 62, full retirement age, and 70 can make the long-term financial consequences easier to understand.
It is also worth considering how Social Security fits into a broader retirement plan. Some households have pensions, workplace retirement plans, individual retirement accounts, or personal savings that can help cover expenses while they delay claiming benefits. Others may need Social Security income as soon as they become eligible.
People who continue working after claiming benefits should also understand the separate earnings test that applies before full retirement age. In certain circumstances, employment income above the applicable annual limit can lead to temporary withholding of benefits. This rule is different from the permanent reduction associated with claiming early.
The right strategy depends on individual circumstances rather than a single retirement age that suits everyone. A worker with substantial savings may be comfortable delaying benefits, while someone with immediate financial needs may reasonably choose to claim earlier.
Ultimately, the most important step is to verify your full retirement age, review your benefit estimates, and understand how your claiming date affects monthly payments. The retirement-age schedule has reached its final scheduled level of 67 for people born in 1960 or later, but the financial decisions surrounding Social Security remain personal. Reviewing official information before applying can help you make a more informed decision about when to begin collecting benefits.